
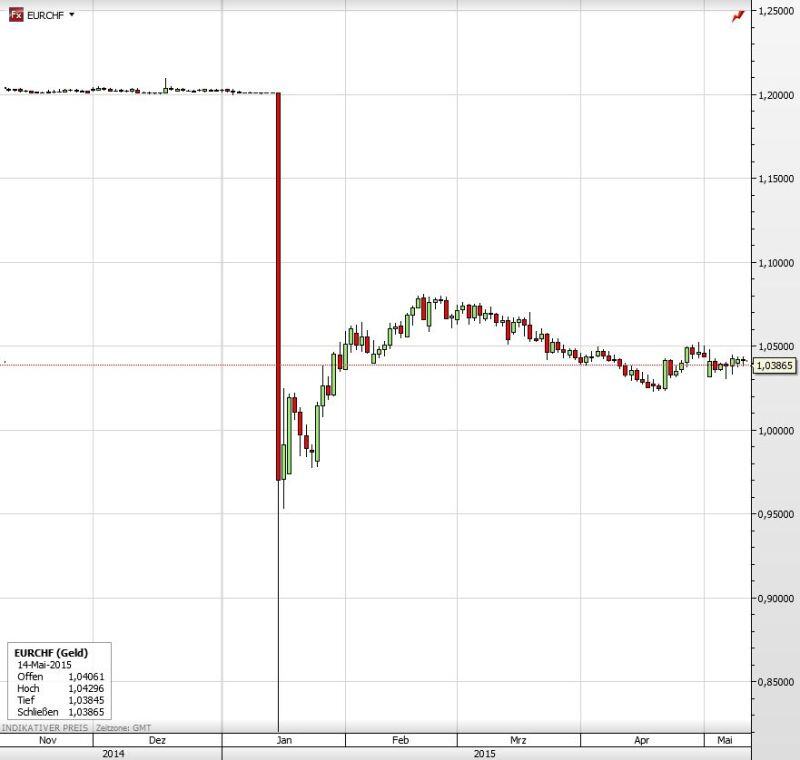
On this day of 2015, the SNB (Swiss National Bank) discontinued the minimum exchange rate of 1.20 EUR/CHF...
Disclaimer
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Related Articles
In June, the SNB warned more forcefully about franc appreciation and signalled an increased willingness to intervene. That exceptional language has now disappeared. Three things changed: → Inflation rose to 0.8% in August. The SNB has raised its forecast, though much of the pressure comes from energy prices and a weaker franc rather than persistent domestic inflation. → Growth surprised on the upside. The SNB now expects Swiss GDP to grow 1.5–2% in 2026, up from around 1%. Pharmaceuticals boosted the headline figure, and capacity utilisation remains below average. → The weaker franc is doing some of the easing. It supports growth while lifting import prices, reducing the case for another rate cut. Our take: A December hike looks premature. But if domestic price pressure builds, the first quarter of 2027 could bring the SNB’s next rate increase. The risk of negative rates has receded. The question now is how long zero lasts.
While I like overnight index swaps if one looks at fed fund futures its pricing in three hikes through spring. Source: Bloomberg