

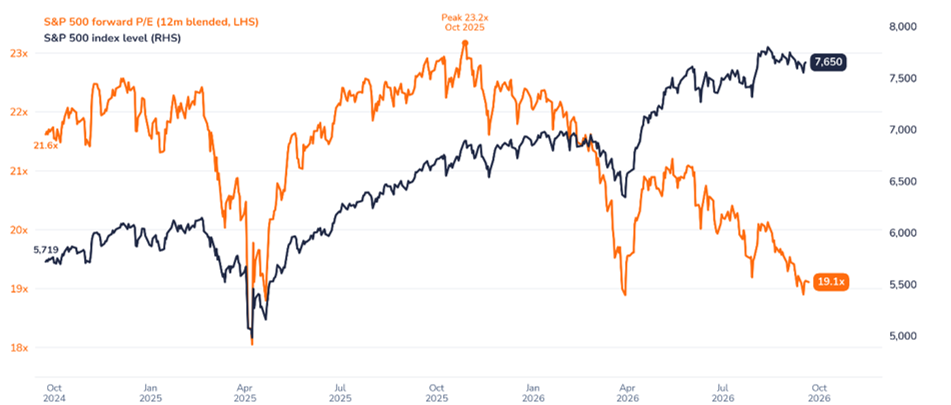
S&P500 price resilience coupled with P/E multiple compression
Source: Bloomberg, Syz Research
We are sorry that for legal reasons we are not able to help US citizens or Canadian residents other than in Ontario, Quebec, or Alberta. Best wishes for the future…
We are sorry that for legal reasons we are not able to help US citizens or Canadian residents other than in Ontario, Quebec, or Alberta. Best wishes for the future…
You chose the following profile. If you made a mistake, please change here USA
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material.
This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor.
This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other
Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
S&P500 price resilience coupled with P/E multiple compression
Source: Bloomberg, Syz Research
Global markets
From Friday 11 to Friday 18 September 2026, global equities moved through a dense run of central bank decisions, most of them well-anticipated rather than market-moving surprises. The Fed delivered its first rate hike in more than three years and the Bank of Japan pushed borrowing costs to a 31-year high, both moves markets had priced with high confidence going in. The MSCI ACWI declined 0.5% over the week, a moderate headline move that reflected less a repricing of the decisions themselves than of the guidance and internal vote splits that accompanied them.
A renewed oil shock added urgency to the tightening narrative. A fresh wave of Houthi attacks on Saudi oil infrastructure, including strikes on an Aramco refinery and fuel terminal, alongside reported disruptions to commercial shipping in the Strait of Hormuz, pushed Brent crude above $100 a barrel. The move contributed to gasoline-driven upside surprises in US CPI and PPI data and was later cited by the Bank of England as a source of upward rate risk. That said, the case for Fed action predated the oil shock. Chair Warsh's hawkish Jackson Hole remarks in late August had already shifted expectations, while survey data suggested inflation pressures were broadening beyond energy. Against that backdrop, the FOMC voted unanimously on 16 September to raise the federal funds rate by 25bp to 3.75-4.00%, with Warsh signalling further tightening ahead. Equities initially sold off, with the S&P 500 falling more than 1% intraday, but the reaction proved short-lived. As Treasury yields and oil prices eased, investors returned to AI-linked technology stocks and the market recovered its losses the following session.
The broader backdrop likely helped markets absorb the rate hikes without a deeper drawdown. Over the past year, S&P 500 earnings growth has outpaced the index's own price gains, compressing the forward P/E multiple from around 23x in October 2025 to 19.1x currently, even as the index itself reached fresh highs. That valuation reset means the market is carrying meaningfully less multiple risk vs. a year ago, leaving more room to digest higher rates without the sharper de-rating a richer market might have suffered.
The hawkish shift extended beyond the US. The Bank of Japan raised its policy rate by 25bp to 1.25%, the highest level in 31 years. The Bank of England left rates unchanged at 3.75% but warned that a prolonged Middle East conflict could require further tightening. Against this backdrop, the MSCI AC World ex-USA fell 1.2%, underperforming US equities as higher rates weighed on markets lacking Wall Street's AI-driven support.
Sector performance mirrored the rates narrative cleanly. Rate sensitive sectors - utilities, real estate and regional banks - were among the weakest performers on both sides of the Atlantic, while healthcare provided relative defensiveness. Technology split sharply within itself: warnings from AI executives about the pace and risk of AI capability development briefly unsettled chip names before they recovered, while cybersecurity emerged as the week's standout gainer.
US
The S&P 500 ended essentially flat at -0.1%, a deceptively calm headline that masked the mid-week Fed-driven drawdown and Thursday's recovery. The Nasdaq 100 outperformed, up 0.9%, while the Russell 2000 fell 1.5% as smaller, more leveraged names bore the brunt of the higher-for-longer repricing.
Financials were the weakest large sector, down 2.3%, with investment-grade bank off 4.1% and regional banks down 3.7% as sell-side commentary flagged the risk that a sustained tightening cycle and a flatter yield curve could squeeze net interest margins and capital-markets activity. Utilities (-3.0%) and real estate (-2.0%) also lagged on rate sensitivity, while healthcare (+1.9%) and technology (+1.0%) outperformed.
Within tech, the standout was cybersecurity (Global X Cybersecurity ETF up more than 10% on the week), as warnings from the AI executives drove rotation into security names. Software more broadly gained +2.8%. The Mag Seven again outperformed the market, this week led by Meta (+2.7%) and Alphabet (+3.3%), extending a strong run: on a one-month trailing basis, the Roundhill Mag Seven index is up +5.6%, well ahead of the S&P500’s -0.4%.
Europe
The STOXX Europe 600 fell 1.9%, with losses concentrated in continental markets: the CAC 40 dropped 2.7%, the DAX 2.3%, the FTSE MIB 3.0% and the IBEX 35 2.9%. The FTSE 100 was more resilient at -1.1%, helped by the BoE's hold and the index's heavier energy and defensive weighting.
Banks (-2.2%) and financial services (-2.2%) tracked their US counterparts lower on the same tightening concerns, while telecommunications (-2.5%) and construction & materials (-2.1%) also underperformed. Healthcare was the standout gainer, up 2.9%, and European defence names rose 1.5% as the Middle East escalation kept a geopolitical bid under the sector; insurance (+1.1%) and utilities (+0.7%) benefited from the shift in the rate outlook rather than being penalised by it, a contrast with the US read-through.
Rest of the world
The MSCI Emerging Markets index slipped a modest 0.5%, masking sharp dispersion beneath the surface. Taiwan's TAIEX bucked the global tightening theme entirely, rising 2.0% on continued semiconductor strength tied to AI-related chip demand. Korea (-2.5%), Brazil (-2.7%) and Singapore (-2.0%) fell in step with the broader dollar-driven tightening narrative, while China was comparatively resilient at -0.2%. Japan's equity market slipped 1.2% despite the BoJ's hike, as the yen weakened past 156 against the dollar rather than strengthening; the widening rate gap with the Fed and the board's split vote left the carry trade largely intact, blunting the currency-support effect investors might otherwise have expected from tighter policy.
Equity asset class
We maintain a neutral equity exposure, balancing a constructive earnings outlook against the headwind from higher real rates.
Earnings
The outlook remains constructive, supported by AI-related investment, broadening earnings participation across sectors and regions, near-record margins and resilient management confidence.
Valuation
Valuations remain supported by earnings growth, with forward estimates rising faster than share prices. The S&P 500 trades close to 20x forward earnings, while Europe, Japan and Asia remain closer to historical averages.
Risks
The main risk remains a further rise in real yields, increasing discount-rate pressure, although the Treasury’s expanded long-dated buybacks provide some support at the long end.
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Global equities fell on oil, inflation and trade risk, while a Korea-led memory-chip rally offset losses in EM and rotated tech away from Nvidia.
Global equities were roughly flat over the week to 4 September 2026, as a much stronger than expected US August jobs report and renewed US-Iran tensions pushed oil prices and bond yields higher, reviving the case for a September Fed rate hike. The repricing hit European equities harder than the US, with German and French markets underperforming on rate- and energy-sensitive exposure, while banks and energy stocks outperformed globally. Within US tech, a sharp divergence emerged inside the Magnificent Seven, driven by company-specific news at Meta and Nvidia rather than a shared theme. Brazil was the standout market of the week, rallying on rate-cut expectations and firmer oil prices.
Global equities edged modestly higher over the past week, as a blowout Nvidia earnings beat and a sharp pullback in oil prices lifted risk appetite, only for a hawkish Jackson Hole debut from Federal Reserve Chair Kevin Warsh to reverse much of the optimism by Friday. This report examines the drivers behind the week's gains and reversals across the US, Europe, and emerging markets, including the rotation out of health care and small caps, the AI-driven strength in software and cybersecurity, and the easing of the oil risk premium following new US sanctions on Iran.
Live feeds, charts, breaking stories, all day long.
Our latest research, commentary and market outlooks