

As expected, the FOMC left its key policy rate unchanged at 3.75%–4.00% at its October meeting. The monetary policy statement recorded two dissenting votes among the 12 FOMC voting members. Governor Cook and Cleveland Fed President Hammack dissented from the majority’s view and instead voted for a rate hike in October. Lisa Cook’s decision to dissent in a “hawkish” direction was surprising, as she had generally been regarded as a “dovish” member who favoured looser rather than tighter monetary policy. She had not dissented previously. Hearings involving Lisa Cook are planned for next week and according to Chair Warsh, neither he nor other Fed officials will attend them. The hearings concern another attempt by the Trump administration to find a way to remove Cook from her current position as a Fed governor.
Overall, the FOMC statement was largely unchanged, but the description of current economic growth was revised to say that activity had “expanded at a strong pace”, compared with the September wording of “expanded at a solid pace”. The statement also explained that the FOMC continues to view uncertainty about the outlook as elevated, productivity growth as strong and capital investment as robust, while job gains continue to keep pace with growth in the workforce. It added at the end that the “accumulation of more information will help the Committee to determine the policy stance appropriate to ensure a timely return of inflation to the 2% goal.”
What did Chair Warsh explain during the press conference?
Warsh noted during the press conference that first-half GDP growth had been revised up from 1.8% to 2.4% and that the third quarter appeared even stronger, supporting his view that the US economy had strengthened when viewed through the rear-view mirror.
US GDP growth improved substantially in Q3 compared with Q2, but has recently declined from even stronger levels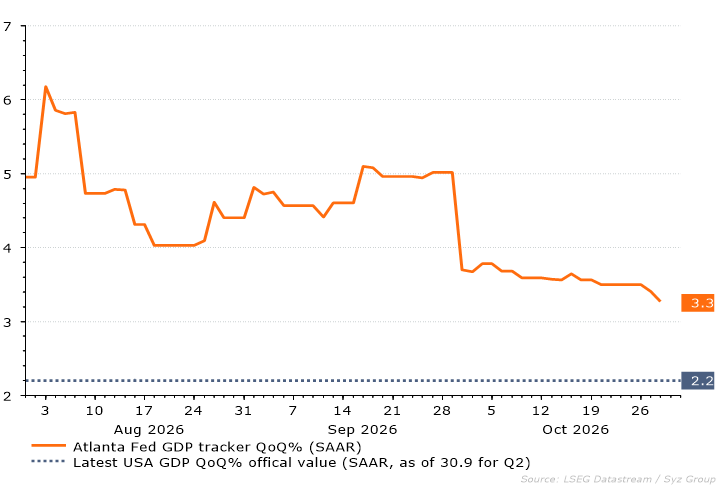
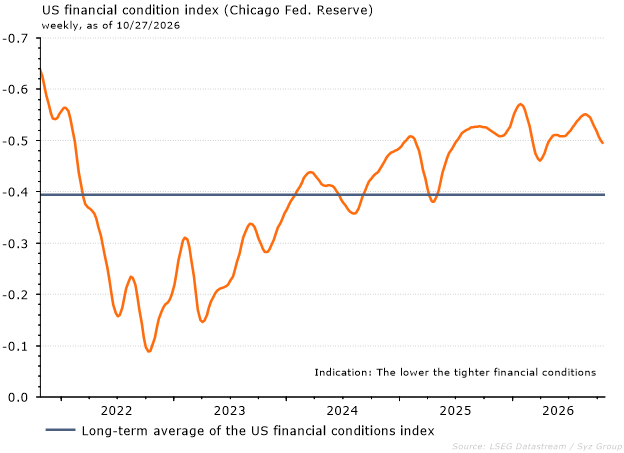
More forward looking, Warsh mentioned that the FOMC believes the September rate increase is starting to restrain activity, although overall conditions are not yet tight: “We have started to see some changes in financial and credit conditions; they have tightened for some businesses and households.” He also added that investors were becoming more selective in allocating capital and that he also regards the AI sector as interest-rate-sensitive: “I don’t believe that they [AI] are somehow divorced from the rest of the economy and interest rates.”
US financial conditions have tightened moderately since early September
As in earlier meetings, investors should not expect reliable guidance on the next interest-rate decision. “I don’t believe in forward guidance, absent exigent circumstances, absent a crisis,” Kevin Warsh said, again reinforcing a more data-dependent and deliberately less predictable policy approach.
In his opening statement, Warsh announced that the FOMC would adjust its meeting schedule. The Fed will create dedicated strategy meetings and hold fewer rate votes. “We believe eight meetings per year is the right number for the FOMC,” Warsh said, “but one meeting in 2027 and two in 2028 will focus on strategy rather than rate decisions.” Asked about the Fed’s task forces, he mentioned that they were not close to reaching any conclusions and that he looked forward to gaining further insights into the key issues facing the Fed through their work.
What did markets do after the statement and press conference?
Financial markets delivered a relatively muted but differentiated response to the Fed’s hawkish hold. The US dollar weakened slightly, while the 2-year Treasury yield declined from its immediate post-statement high. The 10-year yield initially rose, resulting in a steeper yield curve, but later began to decline. US equities remained resilient, with the S&P 500 little changed after the press conference and modestly higher at the close.
What comes next? A rate hike postponed but not abandoned?
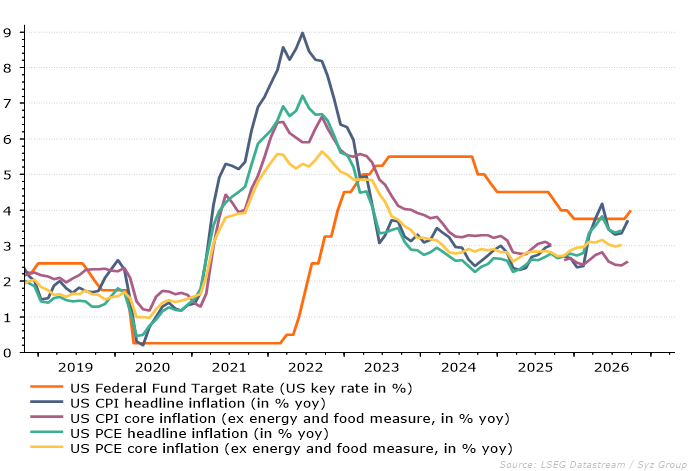
As expected, the FOMC left its key policy rate unchanged, while Warsh delivered a balanced but sufficiently hawkish press conference to prevent markets from repricing the rate-hike path they had priced in before the meeting. Markets still expect a Fed rate hike in December, and we think this is currently the correct assessment: the next hike appears to have been postponed rather than abandoned. Warsh reinforced this perception by mentioning several times that inflation remains above the Fed’s 2% target and that the FOMC is committed to fulfilling its price-stability mandate. He made clear that inflation remains the Fed’s dominant concern. Warsh said the meeting had “focused mainly on the price stability side of our remit,” while describing the employment side of the mandate as “quite positive.”
In 2027, markets still expect one and a half further rate hikes, while we expect only one, delivered during the first half of the year. Our view that the Fed will adjust the degree of monetary accommodation without embarking on an aggressive hiking cycle therefore remains intact. We still expect elevated price pressures to moderate consumption, while somewhat higher yields, wider spreads and tighter, although, as Warsh emphasised, not “tight”, financial conditions should gradually cool economic activity.
Inflation measures remain well above the Fed’s 2% target