
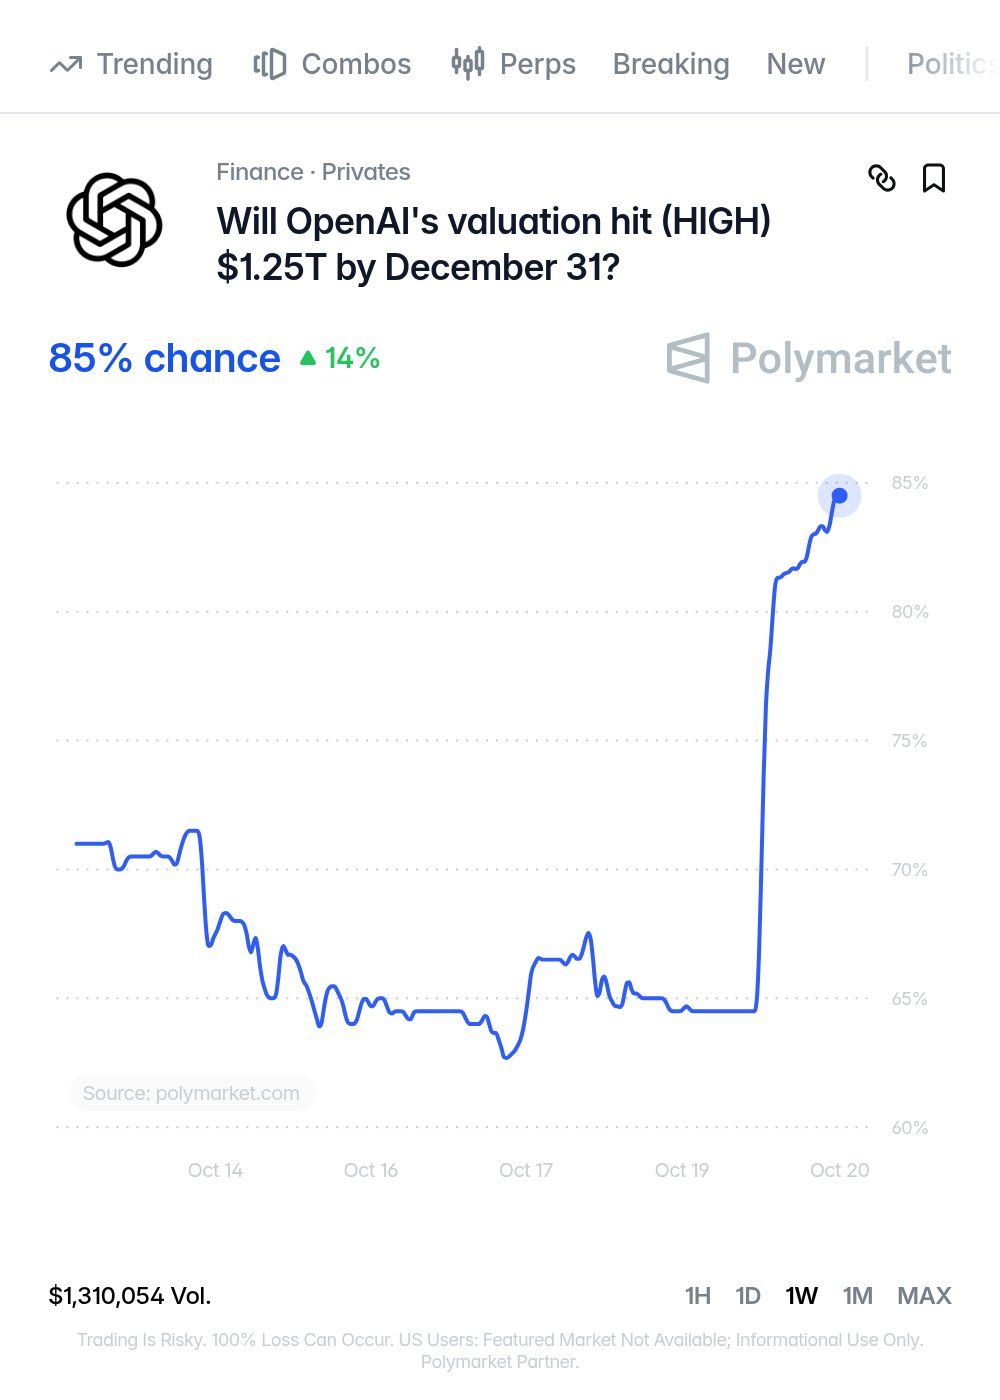
OpenAI's latest fundraising from SoftBank and MGX may be bad news
Disclaimer
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Related Articles
In the meantime, revenue per worker continues to climb. Source: BofA, Lance Roberts @LanceRoberts
Source: The Long View @HayekAndKeynes
A forecast attributed to JPMorgan puts global AI compute demand at roughly 530 GW by 2031. Projected supply? 250 GW. That leaves a 280 GW shortfall—even as supply potentially quadruples between 2025 and 2031. The projected gap would grow from around 50 GW today to nearly 280 GW. The investment implications extend across the infrastructure stack: → Neoclouds: Nebius ($NBIS) and CoreWeave ($CRWV) could benefit from sustained demand for scarce GPU capacity. → Chips: NVIDIA ($NVDA) and AMD ($AMD) supply the accelerators. → Memory: Micron ($MU) helps address growing memory requirements. → Physical infrastructure: Networking, storage, electricity and cooling determine how much capacity actually comes online. Persistent shortages could support pricing, utilisation and longer contracts. Execution, financing costs and hardware depreciation will still determine investor returns. Much of the debate centres on whether AI companies are spending too much. These projections raise another question: Can the industry build fast enough to meet demand? Chips must be manufactured. Power secured. Data centres connected. If this scenario plays out, some of AI’s biggest winners could be the companies removing those bottlenecks. Source: JPM, Milk Road AI