
Disclaimer
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Related Articles
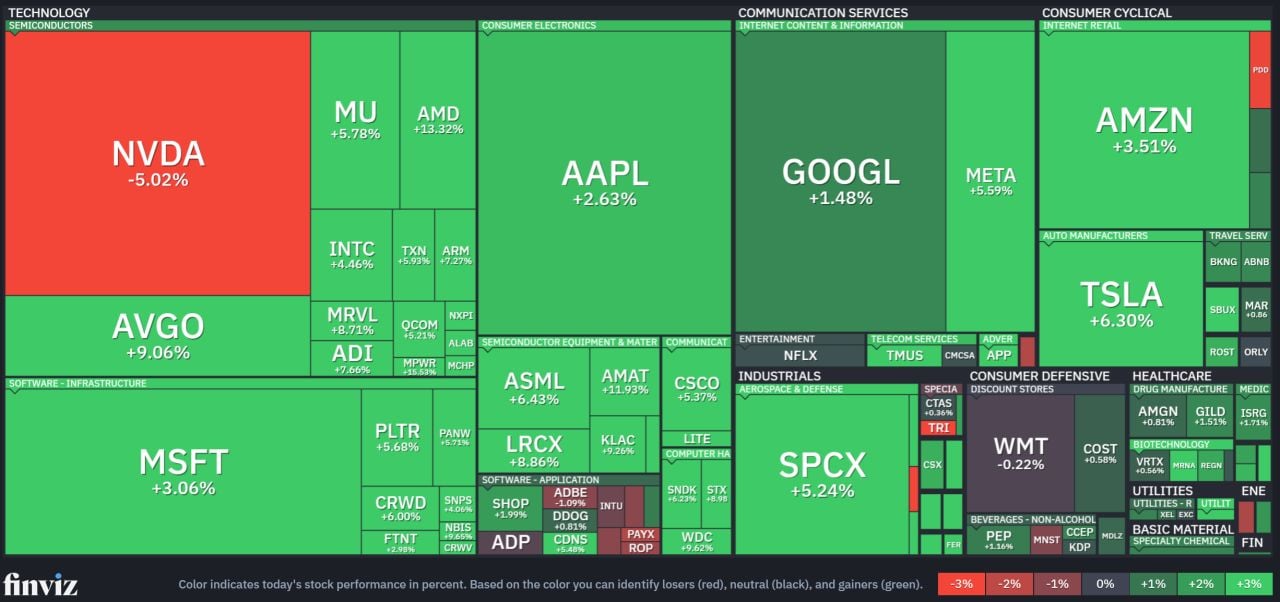
Morgan Stanley’s weekend note had a one-word title: “Shopping.” The call? Buy the drop. The bank thinks the market overreacted to the midterms and priced in a deeper slowdown than its forecasts suggest. 1️⃣ The AI buildout is taking longer. Morgan Stanley estimates that roughly 5 GW of US data center projects, about 20% of those slated for 2028, could slip into 2029. Its hyperscaler capex forecasts still stand at $1.6 trillion for 2027 and $1.8 trillion for 2028. Slower additions could keep compute rents elevated. 2️⃣ A year’s delay matters more when you borrow to build. Microsoft, Amazon, Alphabet and Meta have the cash flow to keep investing. Debt-funded operators have to carry financing costs for longer before new capacity starts generating revenue. 3️⃣ Nvidia remains the top pick. Software could lead the next leg. Morgan Stanley sees upside in Nvidia, Broadcom and memory names. But the most interesting part of the call is where it sees future outperformance. Software and cybersecurity companies such as Snowflake, Datadog, Cloudflare, ServiceNow, Palo Alto Networks and CrowdStrike could benefit as customers put all that compute to work. The risk is a 2028 order gap. If tighter permitting or power constraints turn delays into a broader pause, hardware inventories could build and suppliers could lose pricing power. That’s the tension behind “Buy the Drop.” The same delay that supports rents for data centers already online could squeeze the companies selling equipment for the next wave. Source: Frenchie on X
Anthropic is targeting Thursday or Friday next week, Nov. 19-20, to begin trading on the Nasdaq under ticker $ANT The company plans to unveil its IPO valuation range early this week, with some major investors pushing for a valuation below the previously expected $1.5T. - WSJ The current implied market cap on Liquid is $1.69 Trillion Source: Wall St Engine
Hence the market rebound this week? Source. zerohedge