Charles-Henry Monchau, CFA, CMT, CAIA

Chief Investment Officer

Chart #1 — 

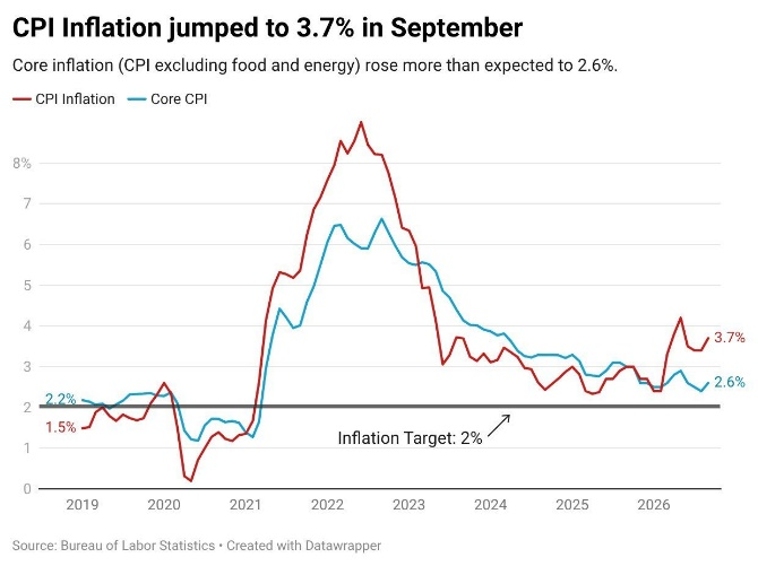
US inflation is heating up again

Headline inflation rose to 3.7% year-on-year in September, its highest reading since May. Higher gasoline and diesel prices accounted for much of the rise, while airfares and used-car prices added to the pressure. Monthly inflation reached 0.6%, the largest increase since May.

Stripping out food and energy, the picture also worsened: core inflation climbed to 2.6% from 2.4% in August, above expectations. Households are clearly being squeezed: prices have risen 3.7% over the past twelve months, ahead of average wage growth of 3%.


Source: BLS


Chart #2 — 

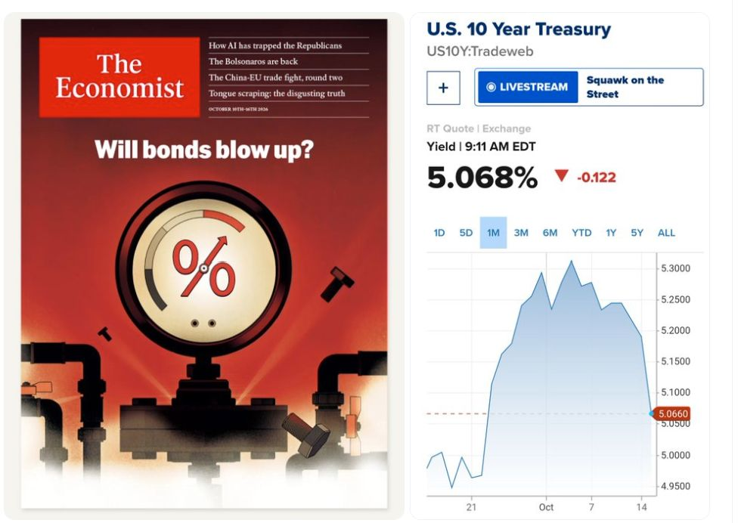
The power of magazine cover stories

US Treasury yields are falling sharply, even though US CPI and PPI inflation figures came in above expectations. The move comes only days after The Economist ran a cover story asking whether the bond market was about to blow up.

Magazine covers have frequently proved to be strong contrarian signals for investors.


Source: Ryan Detrick 


Chart #3 — 

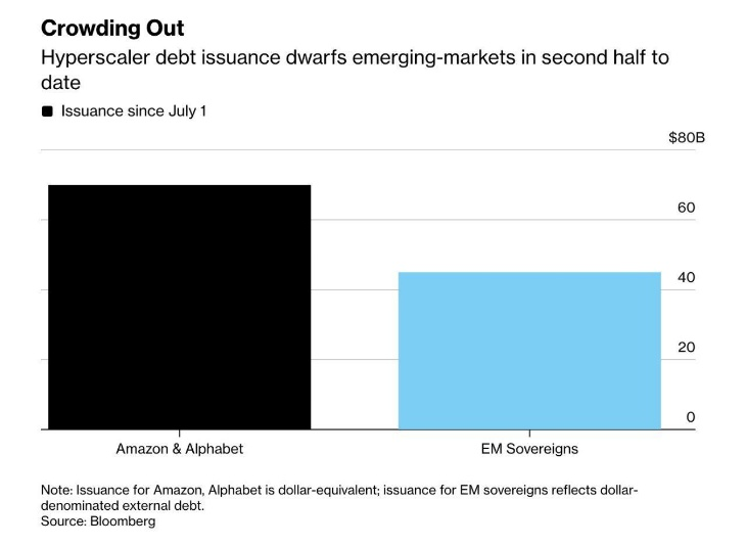
So far in H2, Hyperscaler debt issuance dwarfs emerging market 

Since 1 July, two hyperscalers alone (Amazon and Alphabet) have issued more debt than all emerging-market governments combined. Amazon and Alphabet have raised around $126 billion this year, compared with roughly $41 billion for emerging-market sovereigns.

Source: Bloomberg


Chart #4 — 

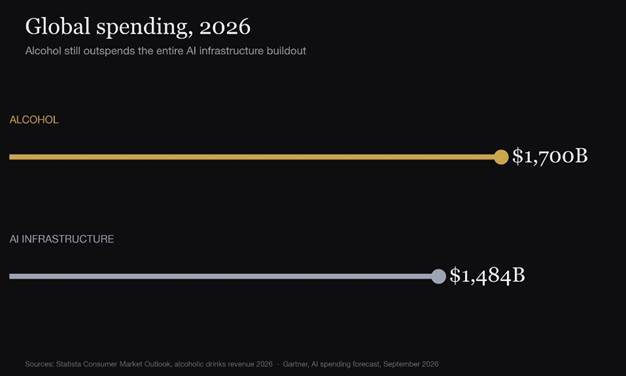
The world continues to spend more on alcohol than AI infrastructure

Spending in 2026:

• Alcohol: $1.70bn

• AI infrastructure: $1.484bn

Forecasts suggest that next year AI spending will overtake alcohol for the first time.

Source: Statista, Gartner


Chart #5 — 

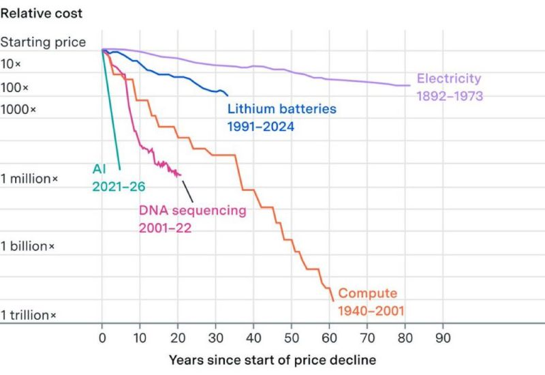
AI’s biggest disruption may be the collapse in its cost

AI costs are falling faster than those of any previous transformative technology, 54 times faster than electricity, and the pace has held steady since GPT-3. Declines that took other technologies decades seem to be unfolding in AI over just a few years. The economic consequences are significant. As intelligence gets cheaper, more tasks become worth automating, personalising or improving. Lower costs can boost demand sharply, even as prices decline.

For investors, this brings both opportunity and pressure. Businesses that use AI could gain from cheaper access, while providers whose products become interchangeable may see their margins squeezed. Surging usage does not necessarily translate into higher profits.

A caveat: the chart neither defines the benchmark used for AI costs nor cites a source. Its striking scale should be verified, and the technologies compared are measured in different units.

Source: Linus Ekenstam


Chart #6 —

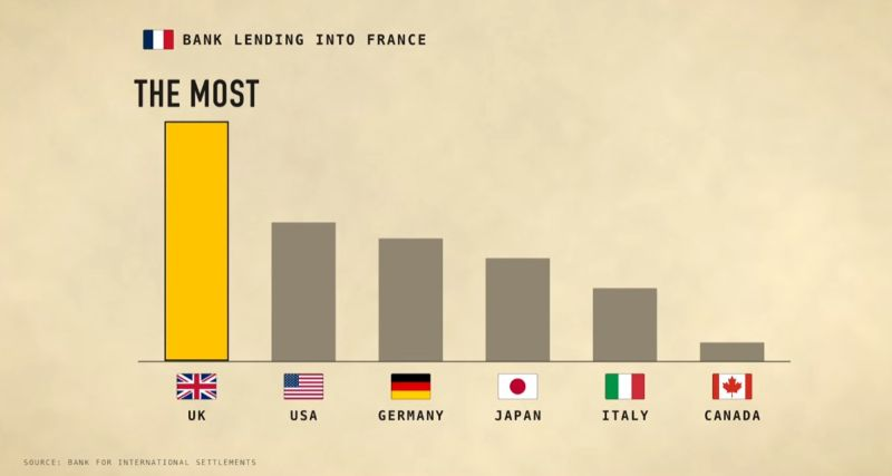
The United Kingdom has purchased the most amount of French bonds out of any nation

This leaves the UK most exposed to contagion and losses should France default on its debt or need a loan from the IMF and the European Central Bank.

When Greece went through this during the 2011 European banking crisis, youth unemployment soared to 60% by 2013.

Source: Financelot


Chart #7 — 

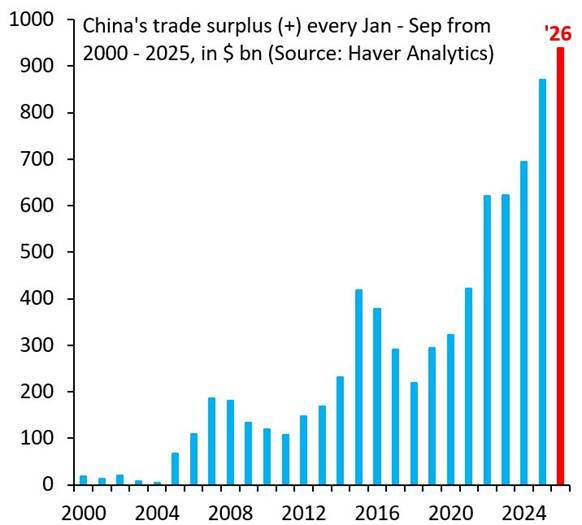
China has a K-shaped economy

September brought China another huge trade surplus of $133.5 billion, as exports jumped 36.3% year-on-year. Hoping that Beijing will move away from export-led growth any time soon seems unrealistic.

The Chinese economy is taking an increasingly K-shaped form:

• The upper arm: exporters and advanced manufacturers are benefiting from global demand for chips, AI infrastructure and green technology.

• The lower arm: households are contending with property-related wealth losses, a weak job market and pressure to pay down debt. Consumption stays subdued as families shore up their finances.

Factories can prosper even as consumers feel worse off. As a result, Beijing relies heavily on foreign demand to offset weakness at home, which makes a swift shift away from exports unlikely. Until Chinese households regain the confidence to spend, the rest of the world will continue to absorb the output of China’s factories.

Source: Robin Brooks


Disclaimer

This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Read More

Straight from the Desk

Syz the moment

Live feeds, charts, breaking stories, all day long.

Thinking out loud

Sign up for our weekly email highlighting the most popular posts.

Follow us

Thinking out loud

Investing with intelligence

Our latest research, commentary and market outlooks