
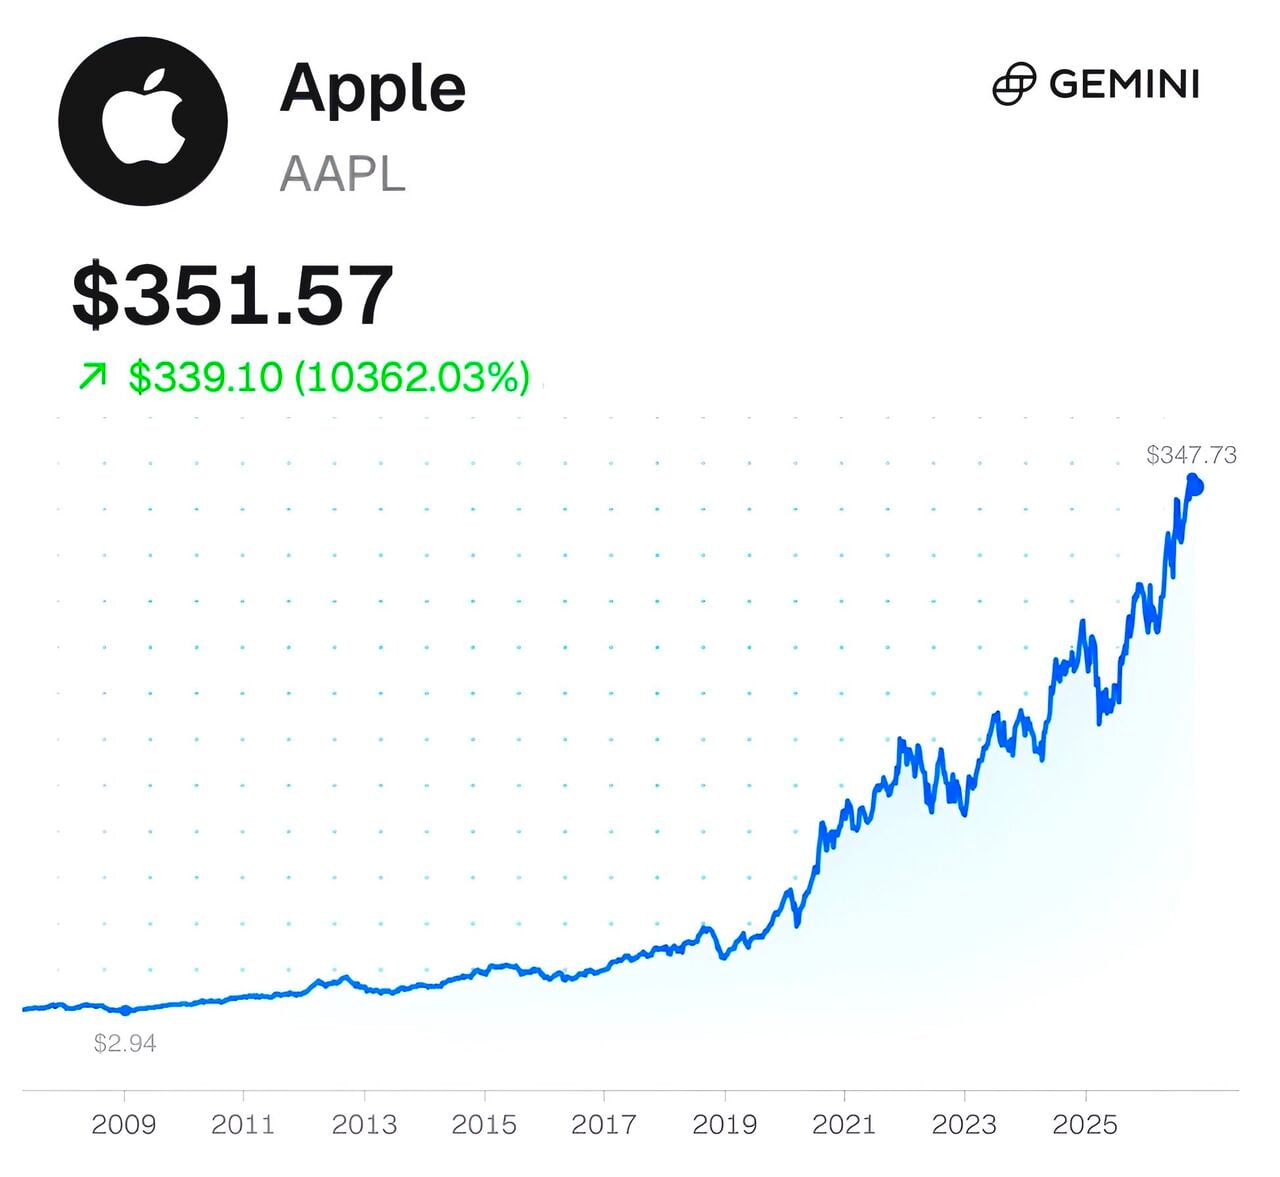
Sometimes you just need to buy and hold...
Disclaimer
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Related Articles
Reuters reported that directors met Wednesday to decide Jensen Huang’s future after The Wall Street Journal reported that the board was preparing to remove him. Bloomberg says Nvidia is working with an outside firm to identify candidates and is considering an interim CEO. The meeting followed Nvidia’s announcement of an independent inquiry into whether Huang was targeted by a foreign intelligence operation. Huang acknowledged being unfaithful in a memo to employees. The New York Times separately reported an alleged affair with an Nvidia executive who reported to him. The Washington Post reported that the White House was staying out of the board’s decision. Huang has led Nvidia for 33 years, oversees dozens of direct reports and has no publicly named successor. Nvidia still has its chips, its order backlog and CUDA. Wednesday’s selloff showed how much investors also value having Jensen Huang in charge. It is also interesting to see that the most powerful proxy of the AI supercycle is being caught in the middle of a human behavior storm… 3 personal thoughts: 1) I don’t think that the departure of Huang will kill the AI story 2) However, market wants to know if his / her successor will be as good as him in terms of execution 3) Nvidia valuation is already on the cheap side; not sure there was a large Huang premium at this price Source: stockmarket.news
The average is 9.9x. Either the market thinks these earnings won't last or this is one of the best setups out there. Source: Rand Group
The stock jumped nearly 8% after-hours The number we are watching: its $1 billion quarterly interest bill. The Q3 numbers show how fast demand for AI compute is growing: ▪️ Revenue hit $3.66B, up 168% YoY ▪️ Adjusted EBITDA reached $2.26B, up 169% ▪️ Revenue backlog surpassed $132B ▪️ Annualized revenue run-rate outlook rose to $20B–$21B Now look at what it costs to build the capacity to serve that demand. CoreWeave expects $35B–$39B in 2026 capex. It also expects $1.05B–$1.15B in interest expense in Q4 alone. That’s more than $4B annualized at the Q4 pace. And even with revenue more than doubling, CoreWeave posted a $529M adjusted net loss in Q3. There is still significant long-term potential. Customers are committing billions, and the backlog gives CoreWeave a substantial pipeline of future revenue. How much cash that revenue generates will depend on what it costs to build and finance the infrastructure behind it. How much of that $132B backlog will translate into free cash flow after capex and interest? That’s the number we want to see. Source: CNBC, Merlin Capital