
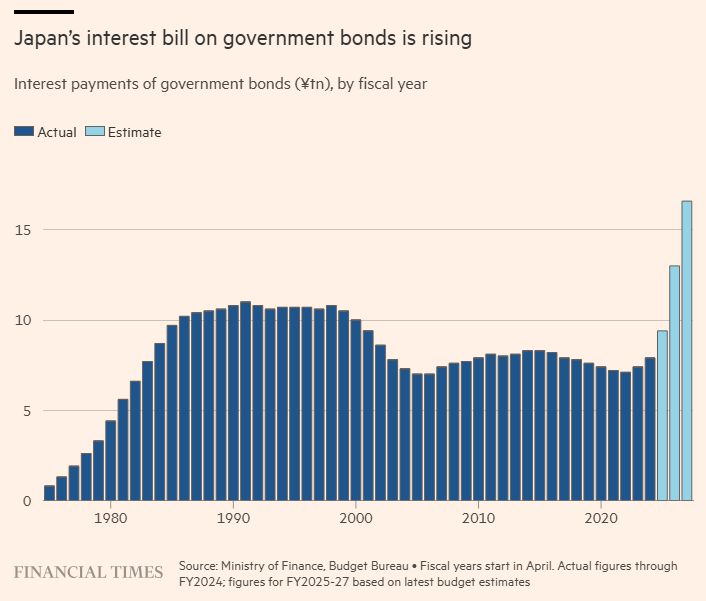
Japan projected to pay an all-time high 16.59 Trillion Yen ($108 Billion USD) in debt interest next year
Source: FT, Barchart
Short positions on the Japanese Yen remain near the largest in history
Source: Bloomberg, Barchart

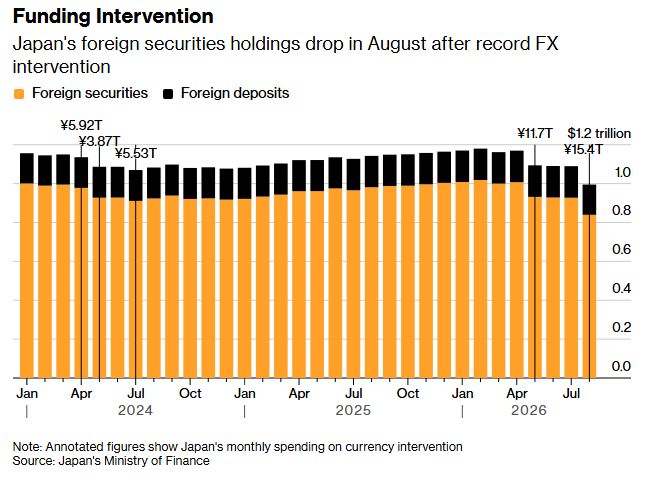
Japan dumped $88 Billion of foreign securities last month, their largest such sale in history
Source: Bloomberg, Barchart
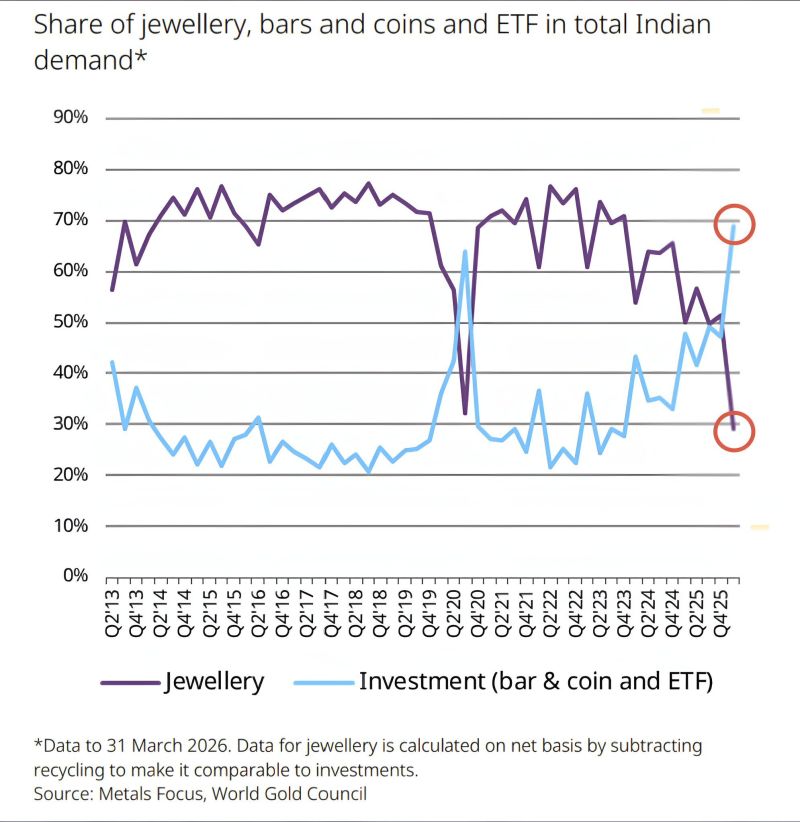
Indians are buying more Gold for Investment than for Jewellery
First time since 2020 Source: Patterns
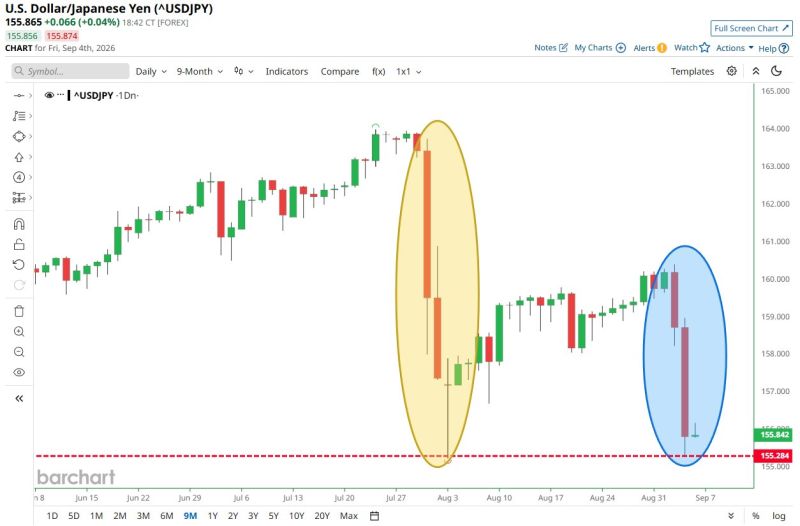
Someone trying to save the Japanese Yen again
Source: Barchart
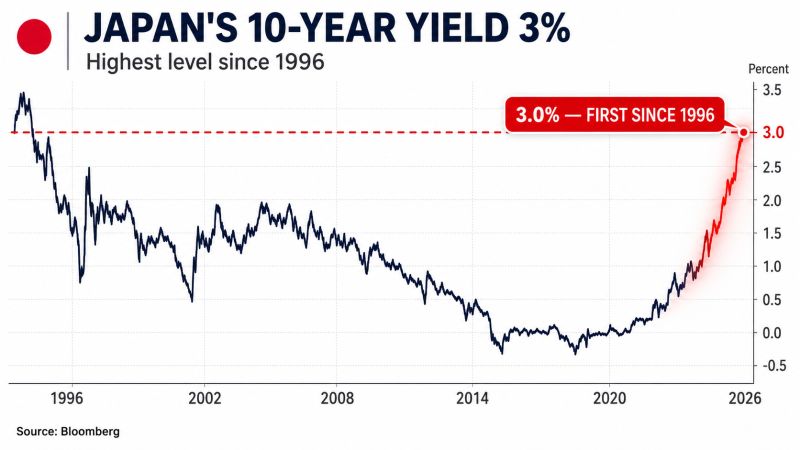
Japan’s bond market has crossed a historic threshold
The 10-year JGB yield has hit 3% for the first time since 1996—doubling from roughly 1.5% in just 12 months. But the bigger story is who now sets the price. Foreign investors account for around 66% of monthly JGB trading volume, up from only 12% in 2009, as the Bank of Japan retreats from negative rates and massive bond purchases. Markets are responding: • A 92% probability of a BOJ rate hike by September • An October increase already more than fully priced in • Record debt-servicing costs of ¥36.6 trillion—around $230 billion—budgeted for the next fiscal year, up 17% For decades, the BOJ dominated Japan’s bond market. Now, market forces are taking control—and the cost of financing the world’s most indebted major economy is rising fast. Investors, not the BOJ, are increasingly setting the price of Japanese debt. Source: Global Markets Investor, Bloomberg
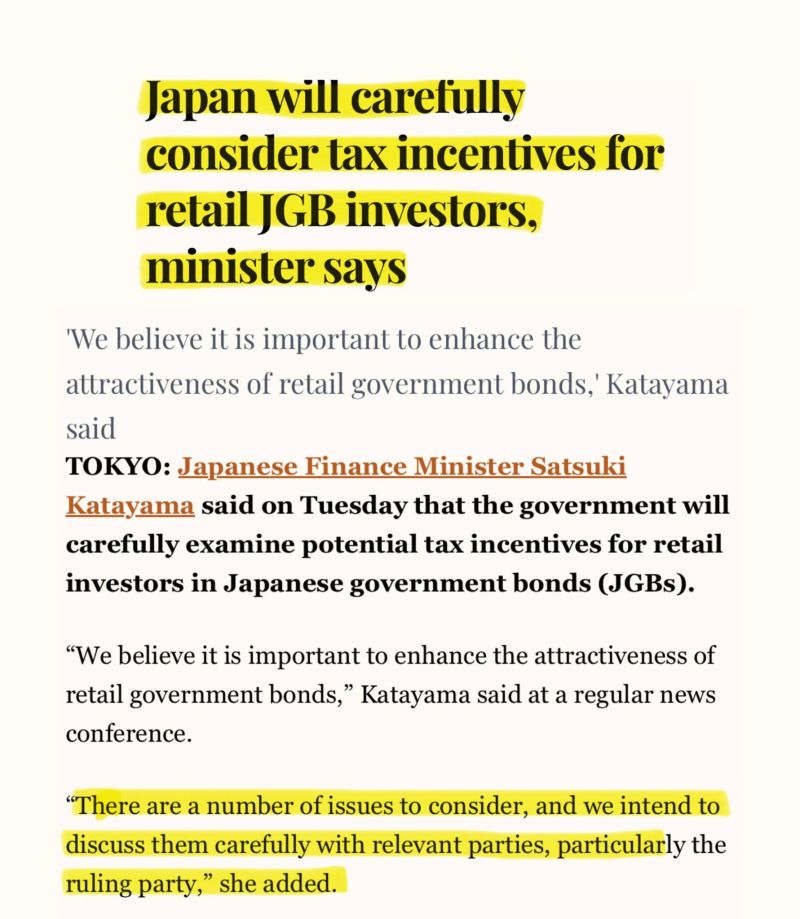
JAPAN IS TRYING TO FIND NEW BUYERS FOR ITS MASSIVE BOND MARKET.
For decades, the Bank of Japan was the buyer of last resort for Japanese government debt. But since 2024, the BOJ has been reducing its bond purchases — leaving a growing demand gap as yields rise. Now Tokyo wants households to help fill it. Japan’s Finance Ministry is reportedly considering adding government bonds to the New NISA tax-free investment program as part of its fiscal 2027 tax reforms. Some lawmakers are even pushing for inheritance-tax incentives. The challenge is huge: → BOJ owns roughly 50% of JGBs → Banks and institutions hold around 40% → Japanese households own just 2% Meanwhile, long-term Japanese yields are trading around levels not seen in decades. Japan spent years using its central bank to absorb government debt. Now it increasingly needs private investors to take over. The big question: Will Japanese households become the bond market’s new buyer of last resort? Source: Bull Theory
For decades, the Japanese yen has been the funding currency of choice for global carry trades.
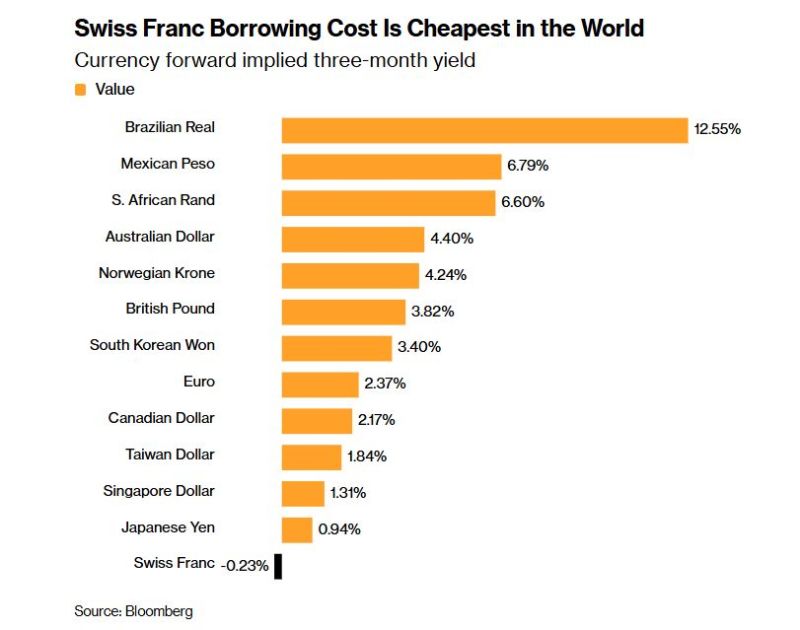
But as volatility in Japan rises and the Bank of Japan gradually moves away from ultra-low interest rates, investors are increasingly looking for alternatives. One currency is emerging as a natural candidate: the Swiss franc. The logic is straightforward. Swiss interest rates remain close to zero, making the franc one of the cheapest major currencies in the world to borrow. At the same time, the Swiss National Bank remains attentive to excessive currency appreciation, reducing—at least in investors’ eyes—the risk of a sharp and uncontrolled strengthening of the franc. Positioning data suggests traders are taking notice. Hedge funds have pushed net short positions in the Swiss franc close to a two-month high, while speculative short positions in the yen have declined for a second consecutive week. The performance differential is already becoming visible. Over the past month, a carry trade funded in Swiss francs and invested in the Mexican peso would have generated a return of roughly 4%, compared with around 1.3% for the same trade funded in Japanese yen. The yen is unlikely to lose its status as the world’s dominant funding currency anytime soon. But the backdrop has changed. Expectations of higher Japanese interest rates, combined with the persistent risk of currency intervention, have made yen-funded carry trades less predictable. By contrast, Switzerland combines extremely low borrowing costs with relatively low interest-rate volatility. That is putting the franc firmly back on traders’ radar. There is, of course, a striking irony in all of this: one of the world’s ultimate safe-haven currencies is increasingly being borrowed to finance risk-taking elsewhere. The Swiss franc may still be a refuge when markets panic—but in calmer times, it is increasingly becoming the fuel behind the carry trade. Source: Bloomberg