
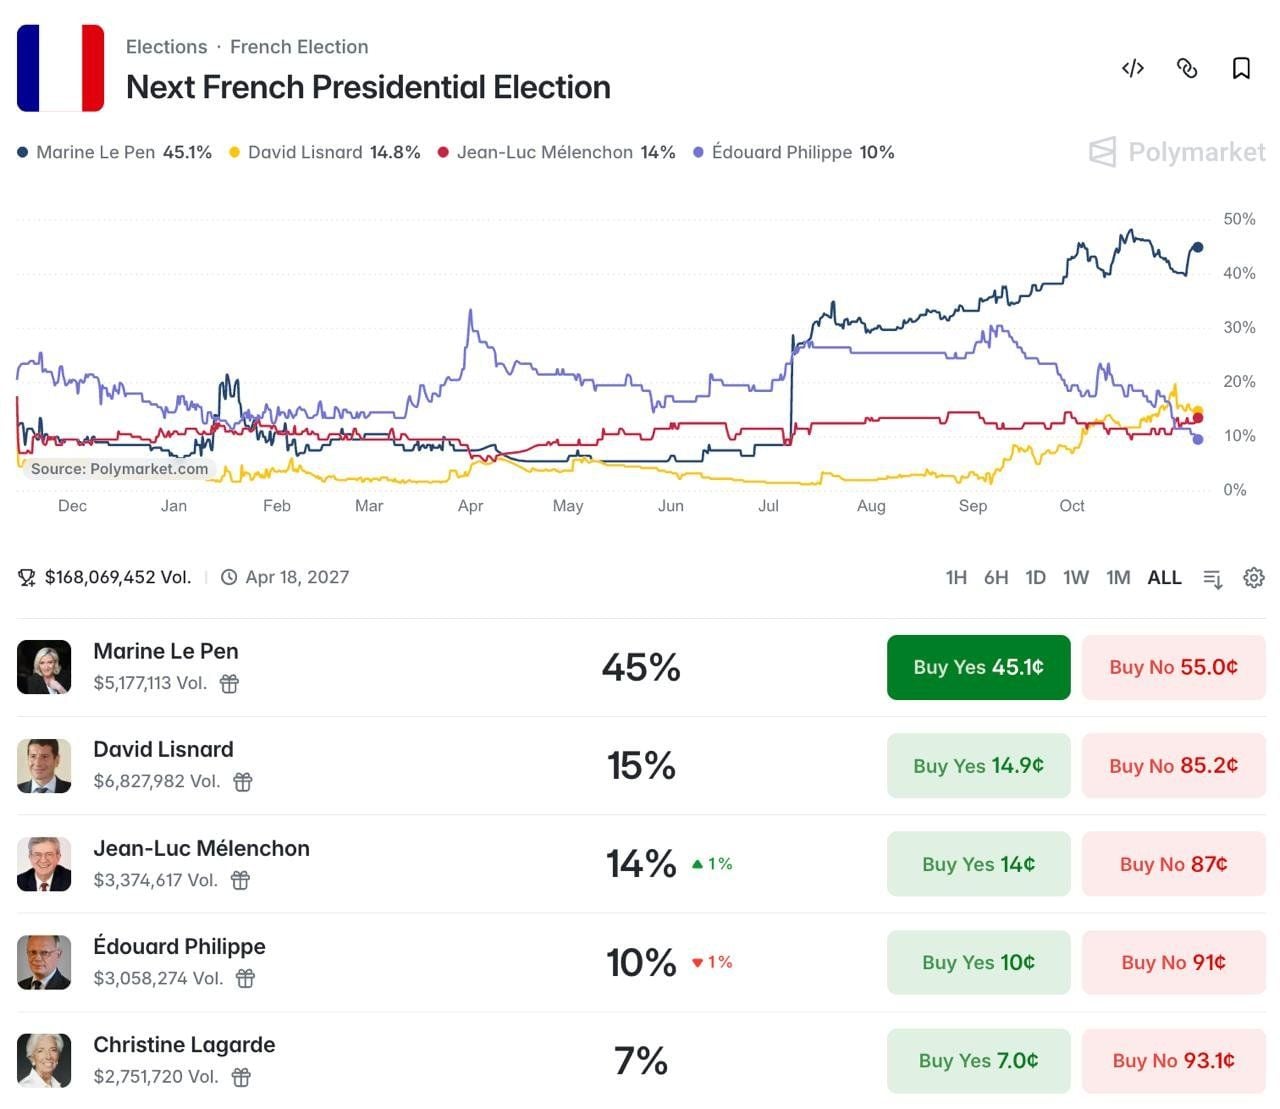
France’s 2027 presidential race: a fragmented centre, an opening for Le Pen. Prediction markets tell a striking story
🥇 Marine Le Pen: 45–47%. The favourite, benefiting from a strong electoral base and divided opponents. 🥈 David Lisnard: 15%. Gaining attention as a pro-business alternative, though his betting odds far exceed his support in conventional polls. 🥉 Jean-Luc Mélenchon: 14%. A loyal base keeps him competitive, but high rejection rates complicate any runoff. 📉 Édouard Philippe: 8.6–10%. Macron’s legacy and competition within the centre weigh on his prospects. 🃏 Christine Lagarde: 6–7%. A potential wildcard, although she has previously ruled out running. The key message? Le Pen’s advantage reflects both her strength and the absence of a convincing challenger. These are betting-market probabilities—not voting intentions. Source. Bloomberg, C.Barraud on X
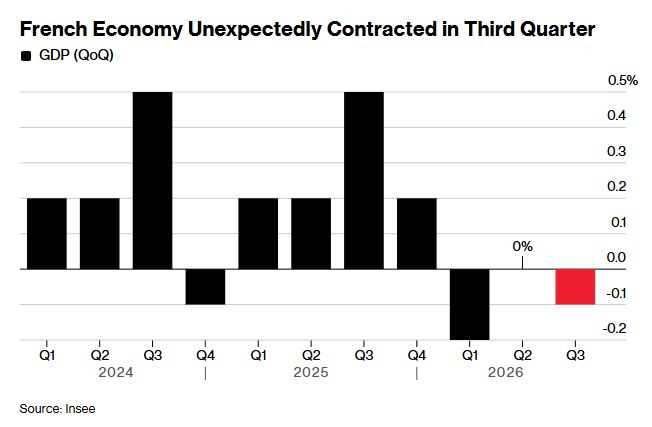
French Economy unexpectedly shrinks as headwinds strengthen
Source: Bloomberg
France: too cheap to ignore?
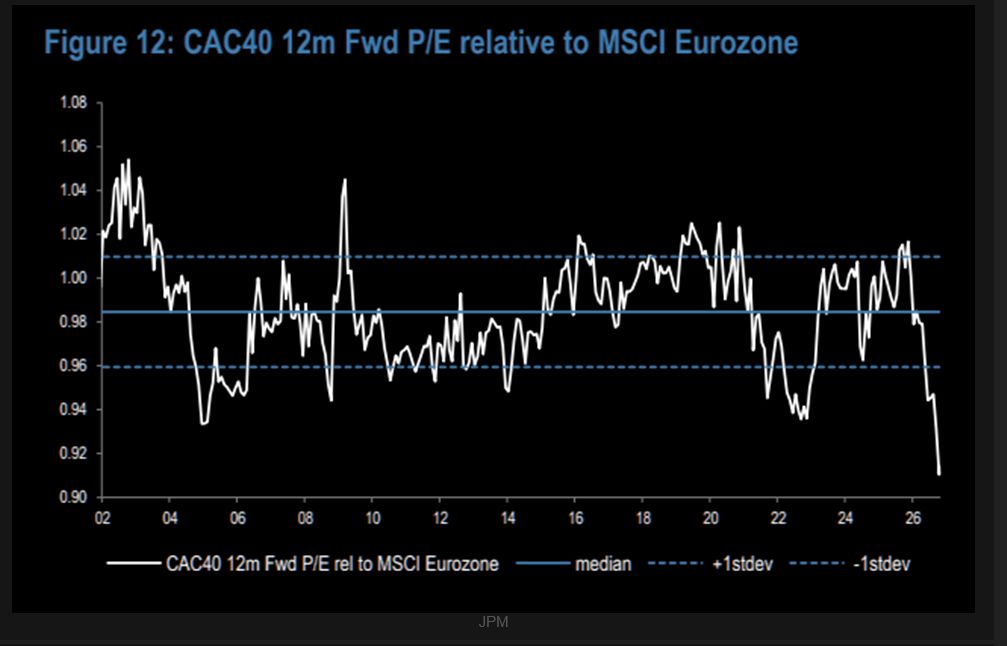
French equities are deeply out of favour—and the valuation gap has reached historic proportions. After more than three years of underperformance, the CAC 40 is trading at its lowest valuation relative to the Eurozone on record, according to JPMorgan. Investors have been retreating from French assets, leaving sentiment firmly in the doldrums. For contrarians, the appeal is clear. The harder question is whether today’s discount offers a genuine opportunity—or simply reflects the risks ahead. Source: JPM, TME
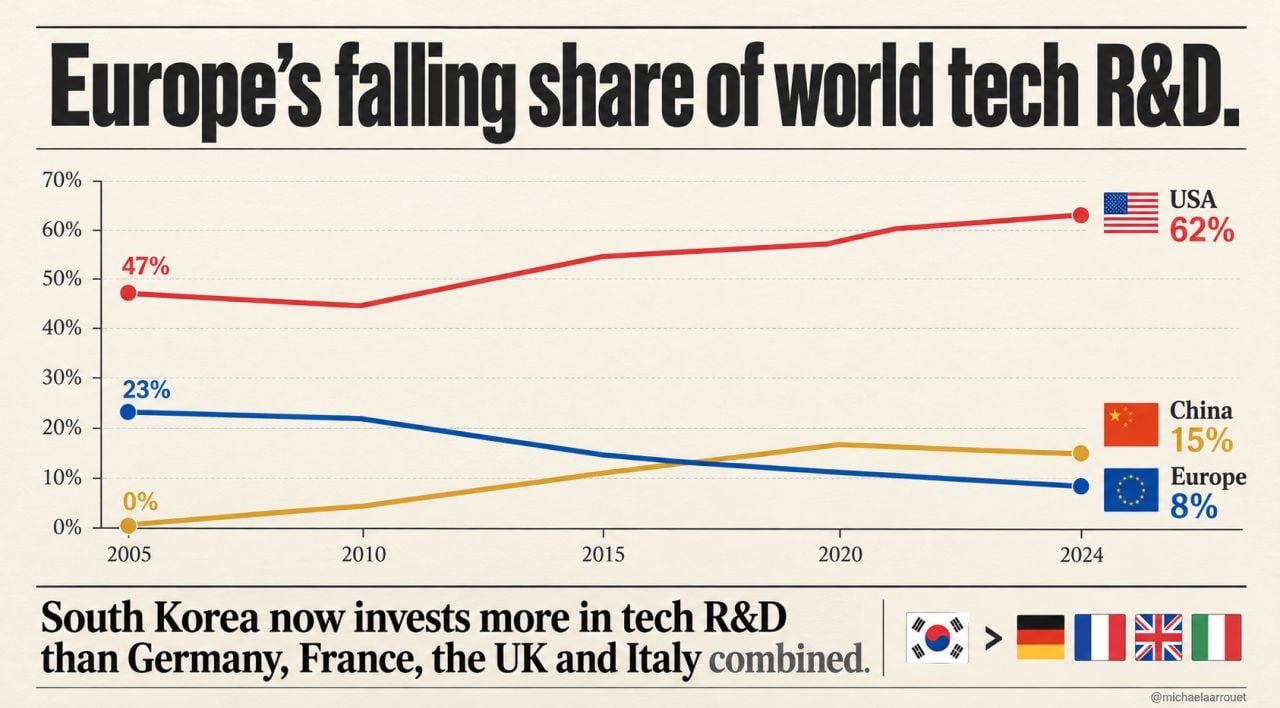
Europe wants to regulate the future. But who will build it?
Europe’s share of global tech R&D: → 2005: 23% → Today: 8% Meanwhile: US: 62% China: 15% South Korea now outspends Germany, France, the UK and Italy. Combined. Europe has talent. Universities. Capital. What it increasingly lacks is an environment that rewards turning ideas into global businesses. Every additional compliance layer consumes resources. Every barrier to scaling pushes opportunity elsewhere. Every reduction in the reward for risk-taking weakens the incentive to innovate. Regulation has a purpose. So does redistribution. But neither can substitute for wealth creation. Europe needs simpler rules, stronger incentives to invest, and greater ambition to build. Because a continent cannot finance tomorrow’s prosperity by regulating yesterday’s success. The choice: build the next generation of global companies—or become an open-air museum for those who do. Source: Michel A.Arouet
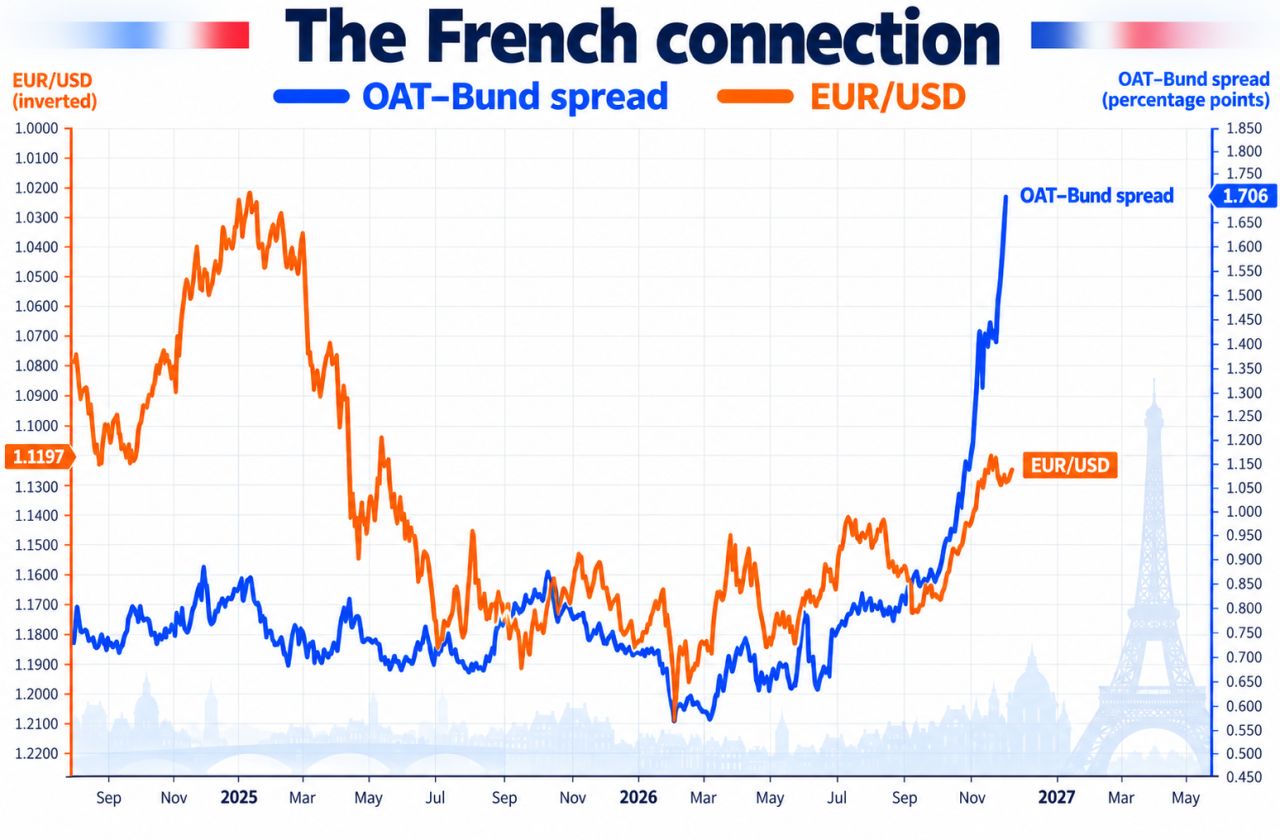
The OAT-BTP spread continues to blow out as France increasingly trades like the European periphery.
Meanwhile, European banks (SX7E) remain under heavy selling pressure. Source. TME
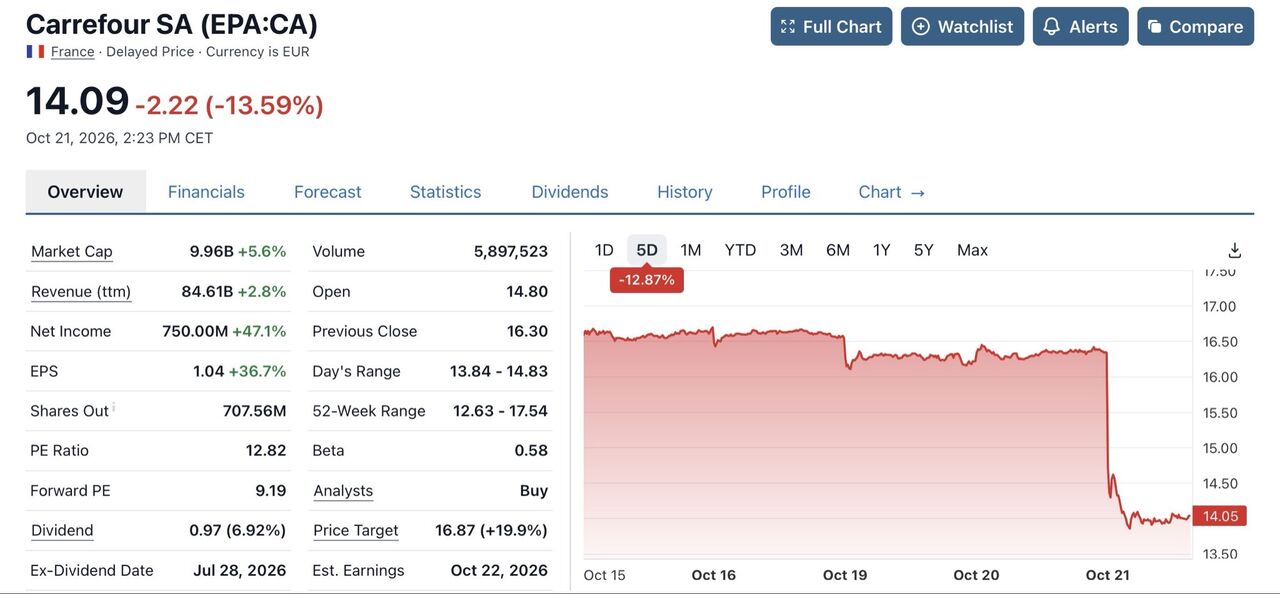
France’s fiscal problem is becoming a corporate earnings problem.
Yesterday (Wednesday), Carrefour reportedly plunged more than 13% after cutting its outlook, warning that looting and store disruptions could cost €80–200 million in operating income. But the damage extends beyond supermarkets. Debt near 119% of GDP. A deficit above 5%. Public spending around 57% of GDP. Now add unrest that hurts confidence, disrupts businesses and threatens tax revenues. The vicious circle tightens: → Persistent deficits require more borrowing. → Higher yields increase interest costs. → Weak growth complicates consolidation. → Political resistance makes reform harder. France is not inevitably heading for a debt crisis. But postponing difficult decisions keeps raising the eventual cost. The risk for Europe? A French fiscal shock would test the eurozone on a scale Greece never could. Source: Michel A.Arouet
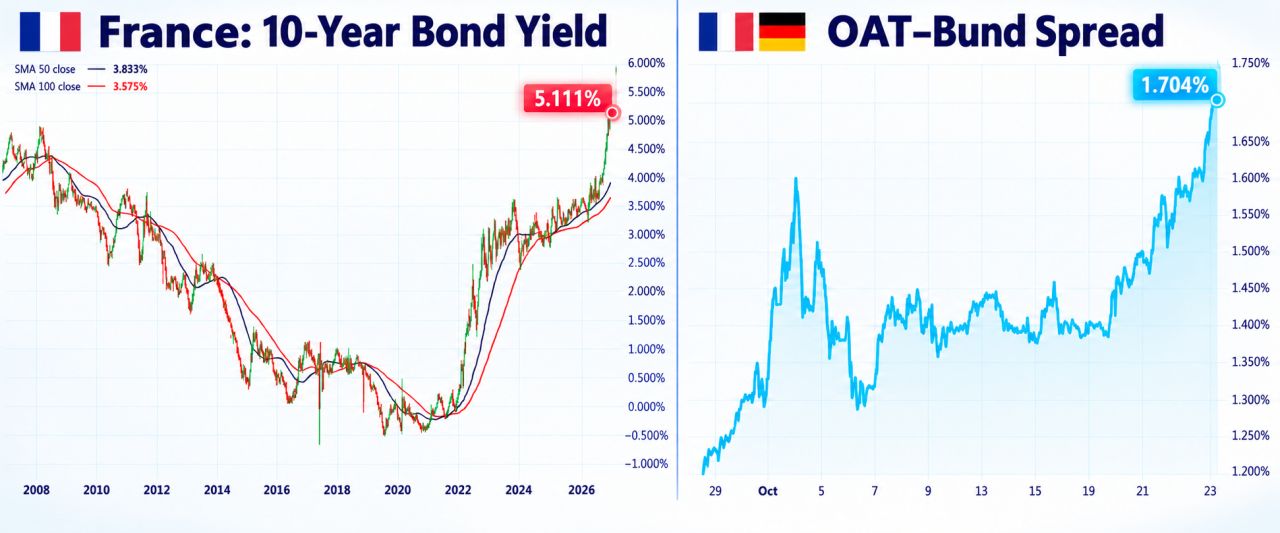
The situation continues to tighten for France on the markets...
🔹10-year yield = 5.11% 🔹OAT-Bund spread > 170 bps Source: Alexandre Baradez
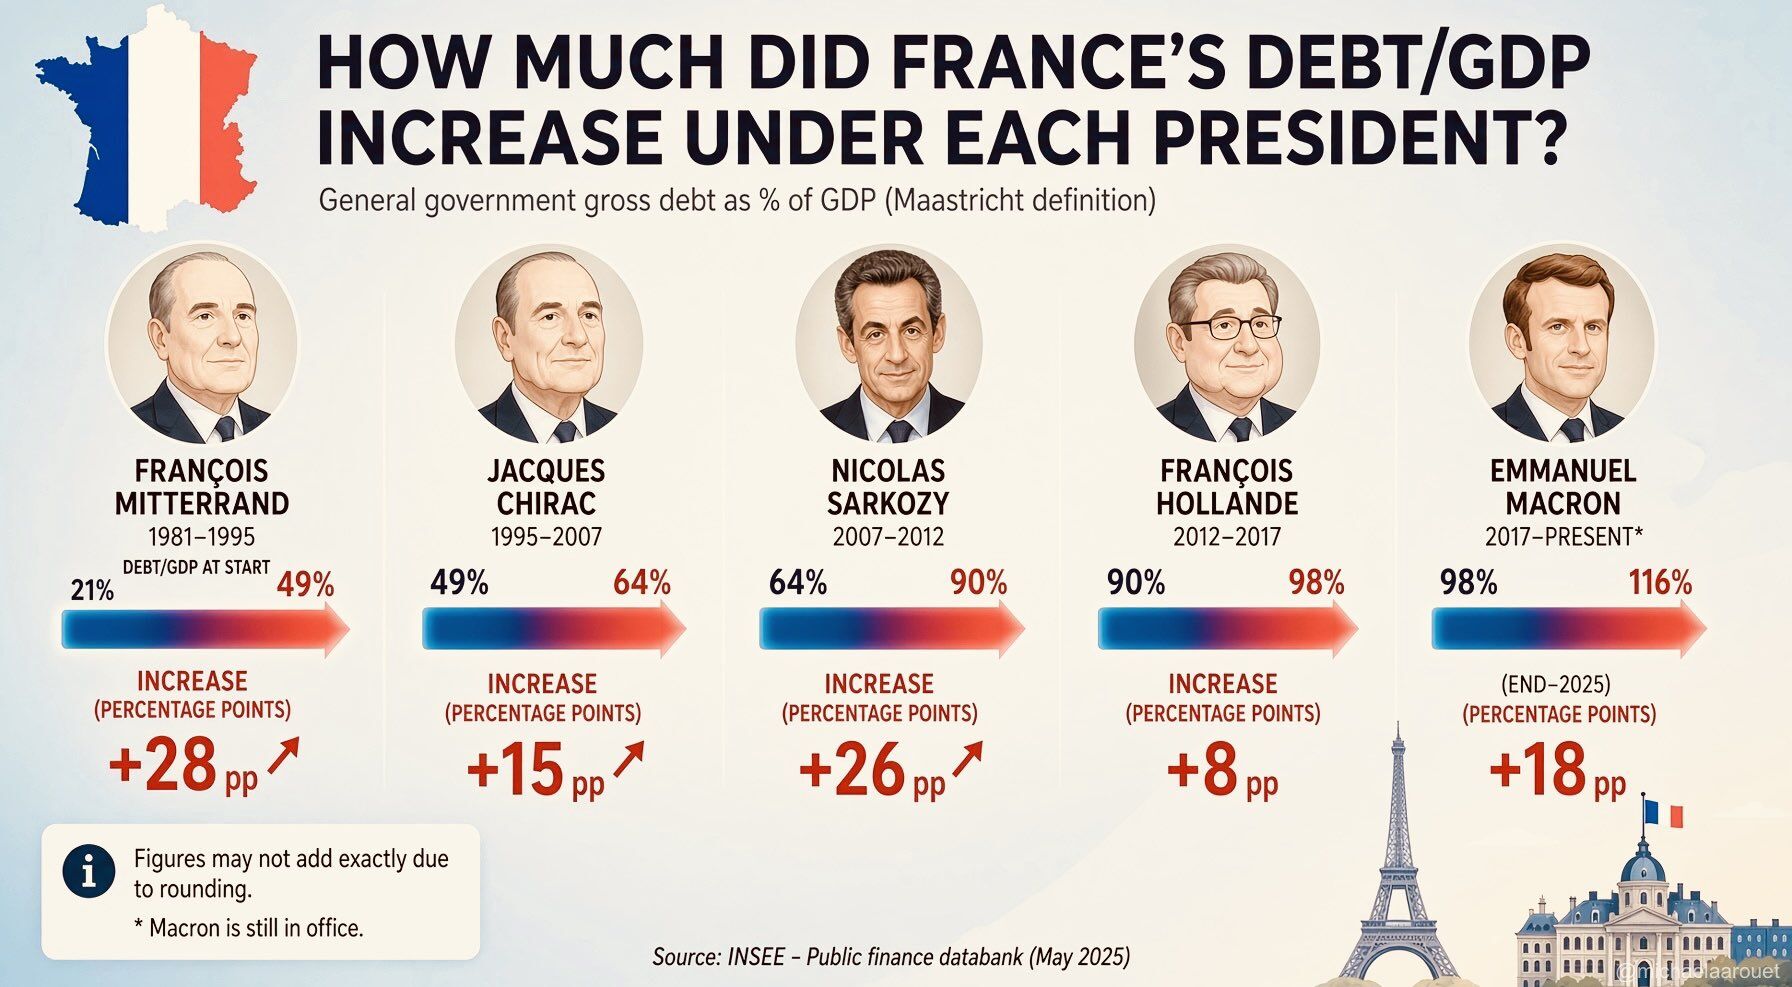
France’s debt problem has no single political owner
Decades of fiscal slippage have pushed debt towards 120% of GDP. Now the arithmetic is tightening: Higher yields → higher interest costs → wider deficits → more debt. Modest growth makes that cycle harder to break. Reforms face fierce resistance. Political instability makes lasting consolidation harder. France’s economic model faces a tougher test as borrowing costs rise and debt accumulates. The question reaches beyond Paris: Can France stabilise its finances before market pressure turns a national fiscal problem into a eurozone crisis?