
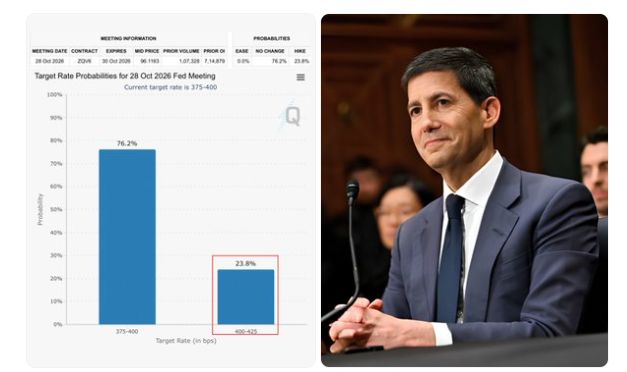
Fed rate hike odds dropped from 70% to 23% in just 4 days as FED officials hint at a pause.
Source: Bull Theory
"Bond Traders can stop panicking when the Fed starts panicking."
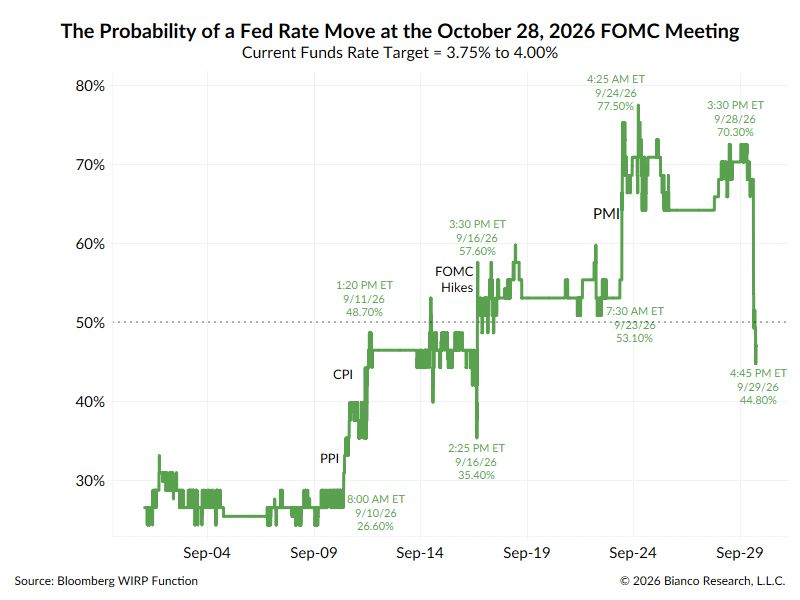
NY Fed Pres John Williams speech yesterday (below) pushed the prob. of a down to hike to 44% (chart). ------------------------------------------------------ New Fed guidance: “There is no need for urgency.” John Williams, the vice chair of the FOMC, delivers notably precise pushback in guiding against an October rate hike that has been getting priced by investors. He lays out his base case: One more hike “may be appropriate late this year.” Here is the key passage from the NY Fed president’s prepared remarks on Tuesday afternoon: “With the policy action we took at our September meeting, there is no need for urgency, and we have time to gather more information. The accumulation of more data should provide greater clarity on the underlying trends in the economy and the associated risks to achieving our goals—and thereby the appropriate setting of monetary policy.” “If the economy evolves in a manner broadly consistent with my forecast, one further upward adjustment of the federal funds target range may be appropriate late this year to support a timelier return of inflation to target. But that is just my forecast, and time—and the totality of the data—will tell.” Source: Jim Bianco, Nick Timiraos
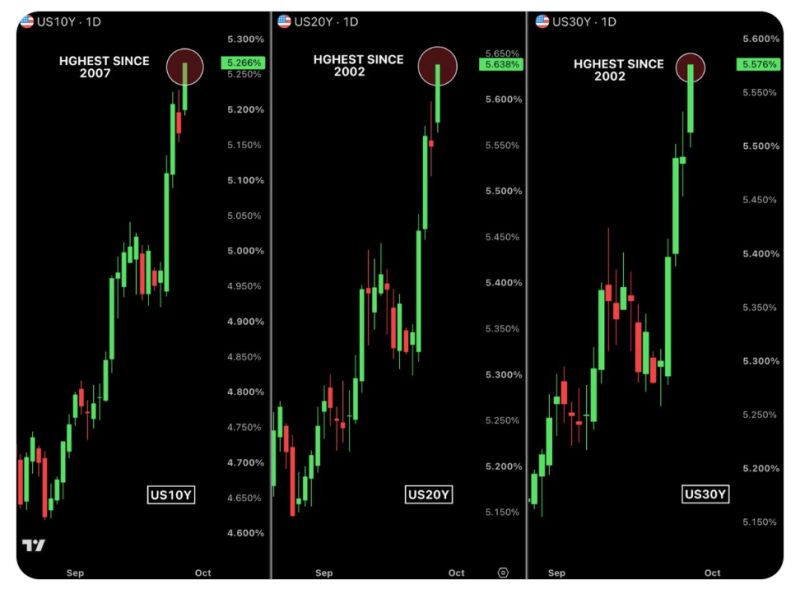
Another day, another multi decade high for US bond yields
Interestingly, US10Y, US20Y, and US30Y have all jumped by 40 bps on average ever since the Treasury Secretary said "I am the house now, bet against me if you dare" US10Y is now the highest since 2007. US20Y and US30Y are both the highest since 2002. Turns out the bond vigilantes took that dare. Source: Bull Theory
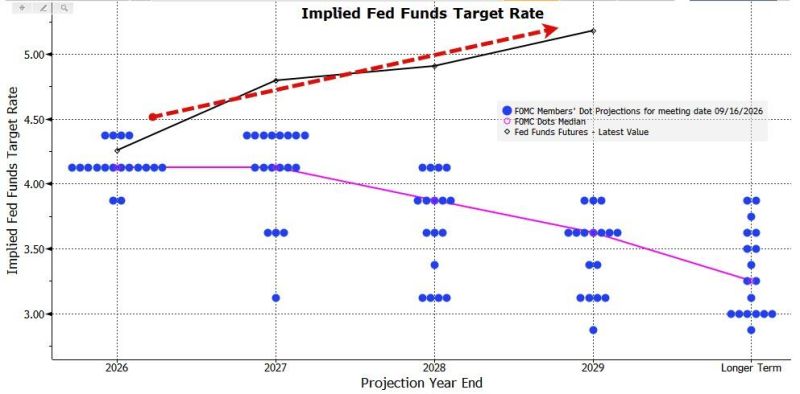
The market now dramatically more hawkishly priced than The Fed's Dots (specifically repricing The Fed's terminal rate expectations)...
Source: zerohedge
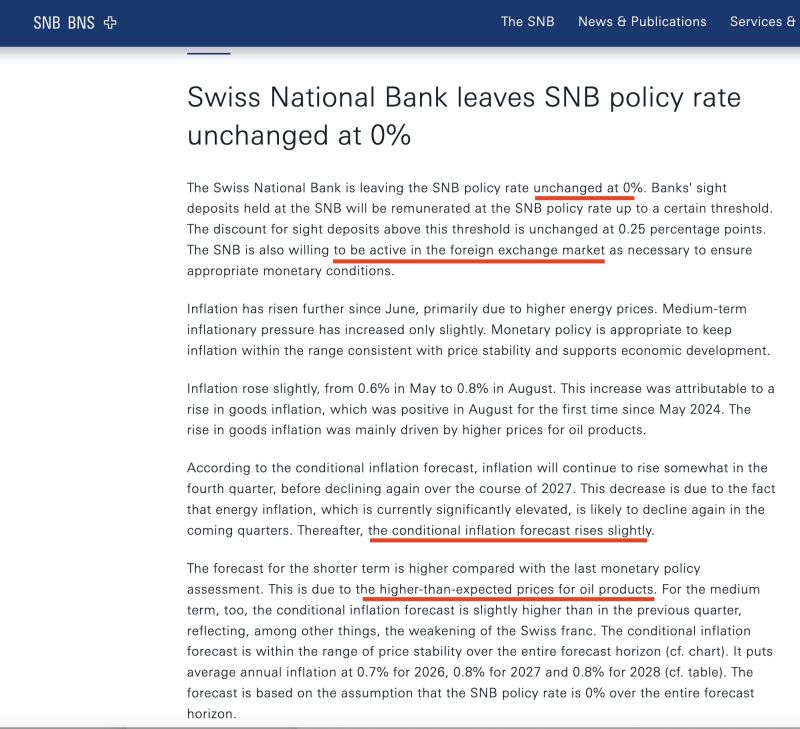
As widely expected, the Swiss National Bank held rates at 0%. But the message has shifted.
In June, the SNB warned more forcefully about franc appreciation and signalled an increased willingness to intervene. That exceptional language has now disappeared. Three things changed: → Inflation rose to 0.8% in August. The SNB has raised its forecast, though much of the pressure comes from energy prices and a weaker franc rather than persistent domestic inflation. → Growth surprised on the upside. The SNB now expects Swiss GDP to grow 1.5–2% in 2026, up from around 1%. Pharmaceuticals boosted the headline figure, and capacity utilisation remains below average. → The weaker franc is doing some of the easing. It supports growth while lifting import prices, reducing the case for another rate cut. Our take: A December hike looks premature. But if domestic price pressure builds, the first quarter of 2027 could bring the SNB’s next rate increase. The risk of negative rates has receded. The question now is how long zero lasts.
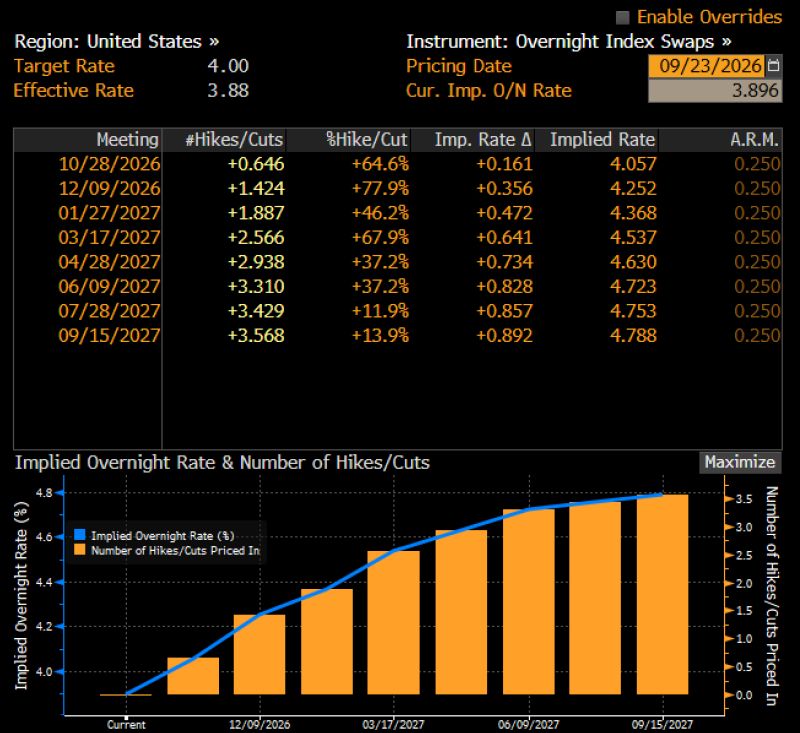
Investors now pricing in three rate hikes through mid 2027.
While I like overnight index swaps if one looks at fed fund futures its pricing in three hikes through spring. Source: Bloomberg
The Fed is hiking again. What's next for stocks?
The first US rate increase in three years lands on a market with accelerating earnings, reasonable tech multiples and abundant financing, but also an energy shock with no visible end date. This cycle does not look like 2022. It can still go wrong.
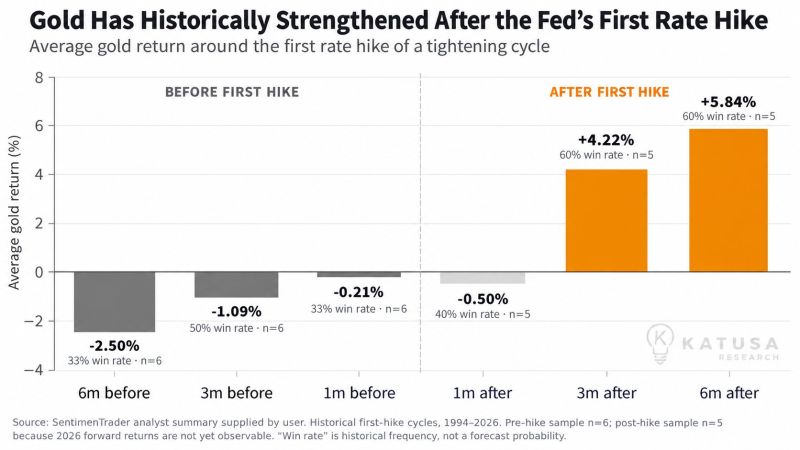
Gold rate hikes have some good historical news for investors.
Source: Katusa Research