
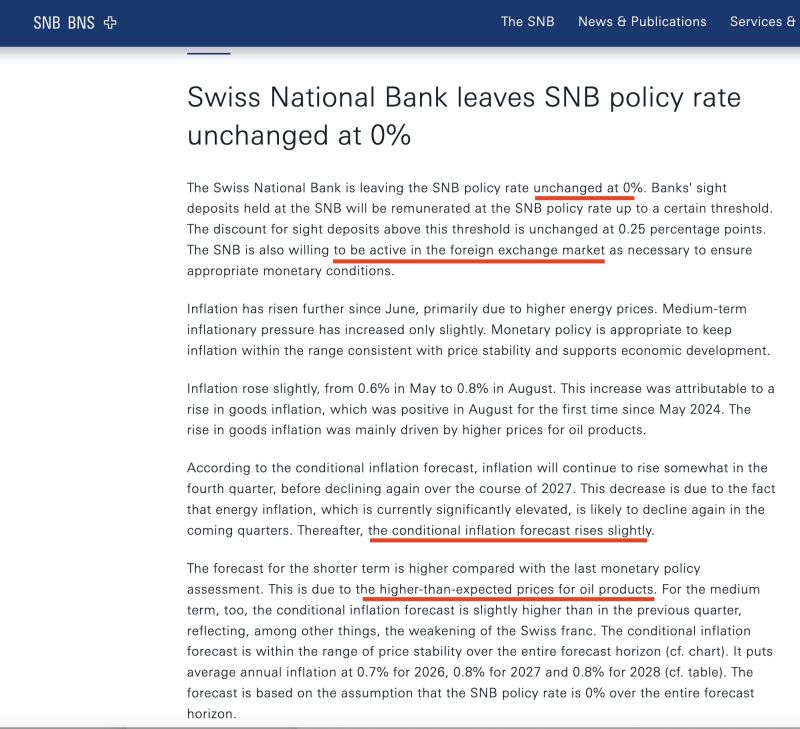
As widely expected, the Swiss National Bank held rates at 0%. But the message has shifted.
In June, the SNB warned more forcefully about franc appreciation and signalled an increased willingness to intervene. That exceptional language has now disappeared. Three things changed: → Inflation rose to 0.8% in August. The SNB has raised its forecast, though much of the pressure comes from energy prices and a weaker franc rather than persistent domestic inflation. → Growth surprised on the upside. The SNB now expects Swiss GDP to grow 1.5–2% in 2026, up from around 1%. Pharmaceuticals boosted the headline figure, and capacity utilisation remains below average. → The weaker franc is doing some of the easing. It supports growth while lifting import prices, reducing the case for another rate cut. Our take: A December hike looks premature. But if domestic price pressure builds, the first quarter of 2027 could bring the SNB’s next rate increase. The risk of negative rates has receded. The question now is how long zero lasts.
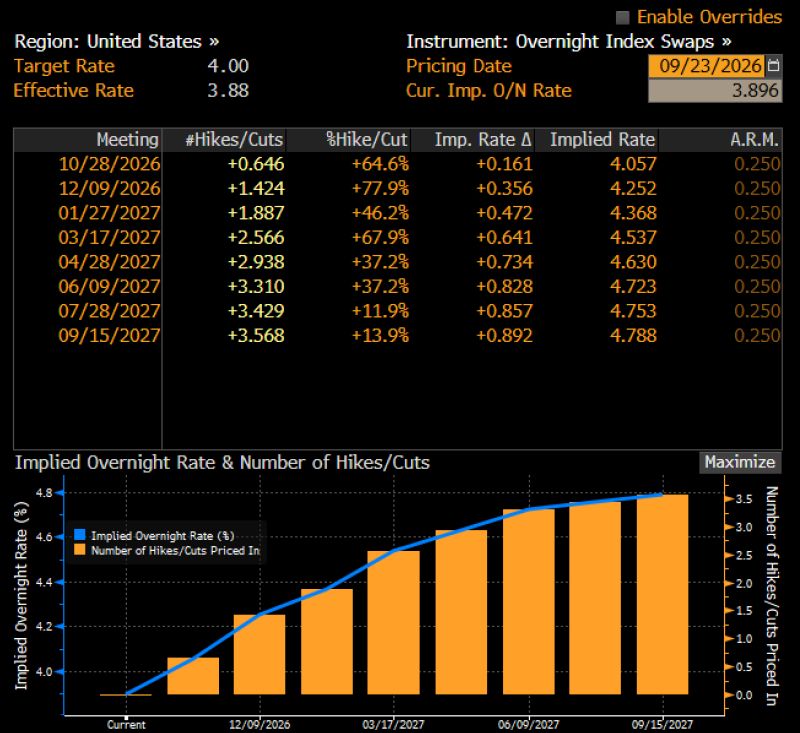
Investors now pricing in three rate hikes through mid 2027.
While I like overnight index swaps if one looks at fed fund futures its pricing in three hikes through spring. Source: Bloomberg
The Fed is hiking again. What's next for stocks?
The first US rate increase in three years lands on a market with accelerating earnings, reasonable tech multiples and abundant financing, but also an energy shock with no visible end date. This cycle does not look like 2022. It can still go wrong.
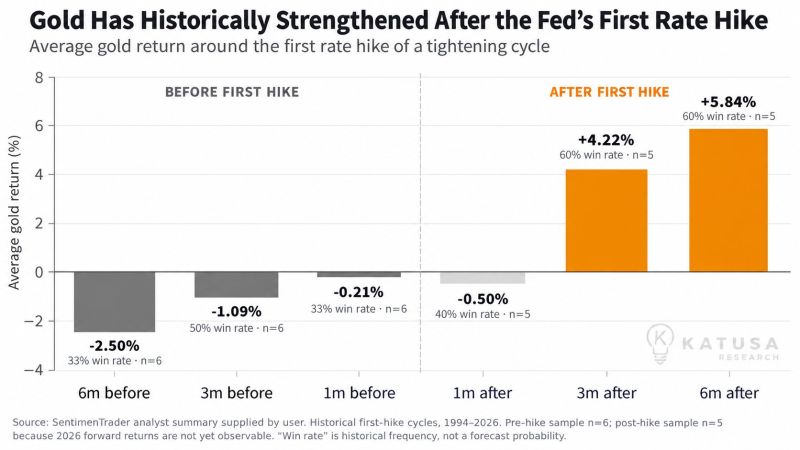
Gold rate hikes have some good historical news for investors.
Source: Katusa Research
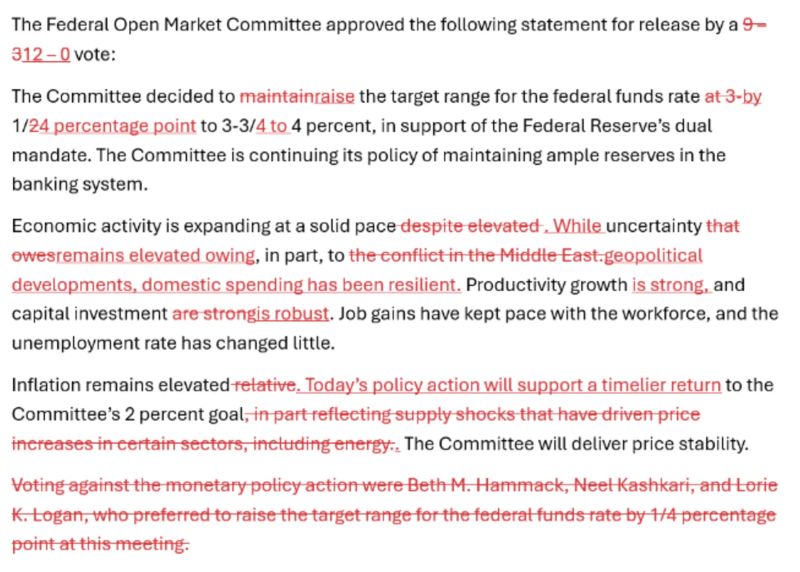
This is a comparison of Wednesday’s Federal Open Market Committee statement with the one issued after the Fed’s previous policymaking meeting in July.
As expected, the Fed raised rates by 25 basis points in a unanimous decision The dot plot showed that 16 of 18 participants expect at least one additional hike this year. However, this does NOT appear to be the start of an aggressive tightening cycle. Policymakers do not project further increases in the federal funds rate over the following years. A unanimous rate-hike decision, and large majority also signaling at least one more hike in 2026 hides the reality that 2027 outlooks are massively divided with four members signaling a 'policy error' implicitly with 3 seeing 2 cuts and 1 seeing 4 cuts... The statement and dots were more hawkish than expected overall as The Fed took away the projected median cut next year. October odds initially declined but then jumped (right before Midterms?) to 57% while December odds of a hike jumped to 75%... While noisy, 2027 rate-hike expectations rose to around 40bps (2026 expectations are now for another 30bps)... 👉 Warsh explained that a resilient labour market, persistent inflation concerns and geopolitical tensions had shifted the committee in favour of a hike. 👉He described the hike as removing a degree of accommodation. In practice, the Fed may be reversing the three rate cuts delivered in 2025—leaving room for UP TO TWO additional hikes. Warsh also suggested that intense competition for capital, particularly from technology hyperscalers, may be contributing to higher US bond yields. 🔴 Conclusion: Yesterday’s hike, and potentially another 25-basis-point increase this year, gives the Fed time to see whether oil prices retreat. A third hike could follow in early 2027 if necessary, fully reversing last year’s easing cycle. Source image: zerohedge
My take on yesterday's FOMC 👇
As expected, the Fed raised rates by 25 basis points in a unanimous decision The dot plot showed that 16 of 18 participants expect at least one additional hike this year. However, this does NOT appear to be the start of an aggressive tightening cycle. Policymakers do not project further increases in the federal funds rate over the following years. A unanimous rate-hike decision, and large majority also signaling at least one more hike in 2026 hides the reality that 2027 outlooks are massively divided with four members signaling a 'policy error' implicitly with 3 seeing 2 cuts and 1 seeing 4 cuts... The statement and dots were more hawkish than expected overall as The Fed took away the projected median cut next year. October odds initially declined but then jumped (right before Midterms?) to 57% while December odds of a hike jumped to 75%... While noisy, 2027 rate-hike expectations rose to around 40bps (2026 expectations are now for another 30bps)... 👉 Warsh explained that a resilient labour market, persistent inflation concerns and geopolitical tensions had shifted the committee in favour of a hike. 👉He described the hike as removing a degree of accommodation. In practice, the Fed may be reversing the three rate cuts delivered in 2025—leaving room for UP TO TWO additional hikes. Warsh also suggested that intense competition for capital, particularly from technology hyperscalers, may be contributing to higher US bond yields. 🔴 Conclusion: Yesterday’s hike—and potentially another 25-basis-point increase this year—gives the Fed time to see whether oil prices retreat. A third hike could follow in early 2027 if necessary, fully reversing last year’s easing cycle. Source image: zerohedge
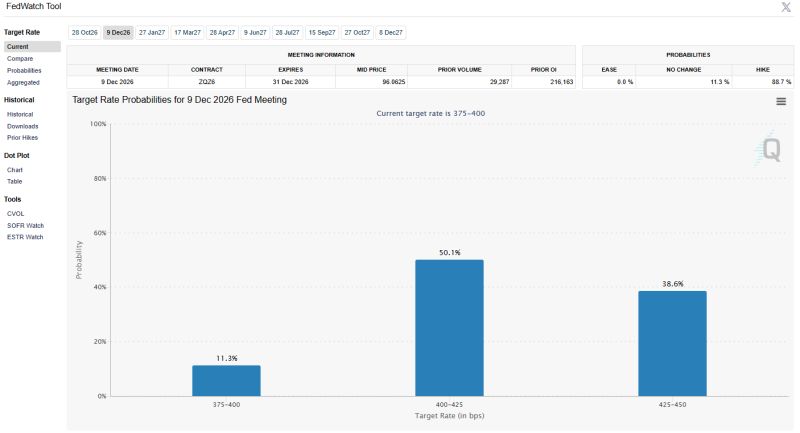
There is now an 89% chance of another rate hike by December
Source: Barchart
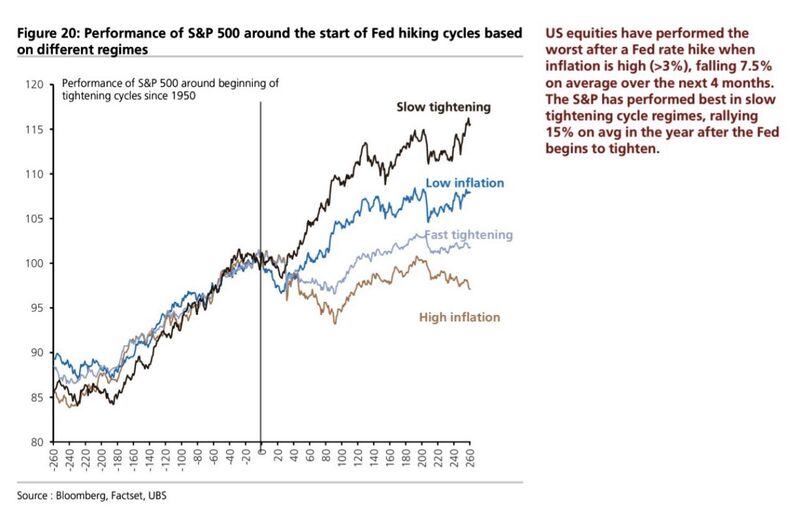
Not all Fed hiking cycles are equal.
Historically, the higher the inflation when the Fed begins to hike, the worse equities have performed. The faster the tightening cycle, the worse equities have performed. Source: David Marlin, UBS, Factset