
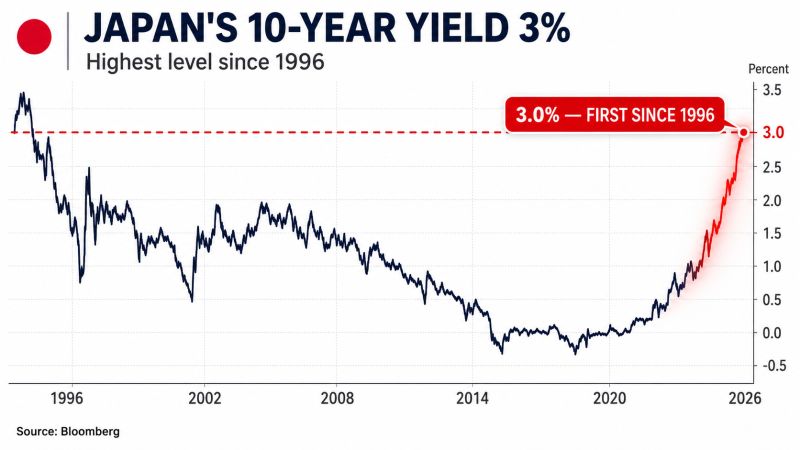
Japan’s bond market has crossed a historic threshold
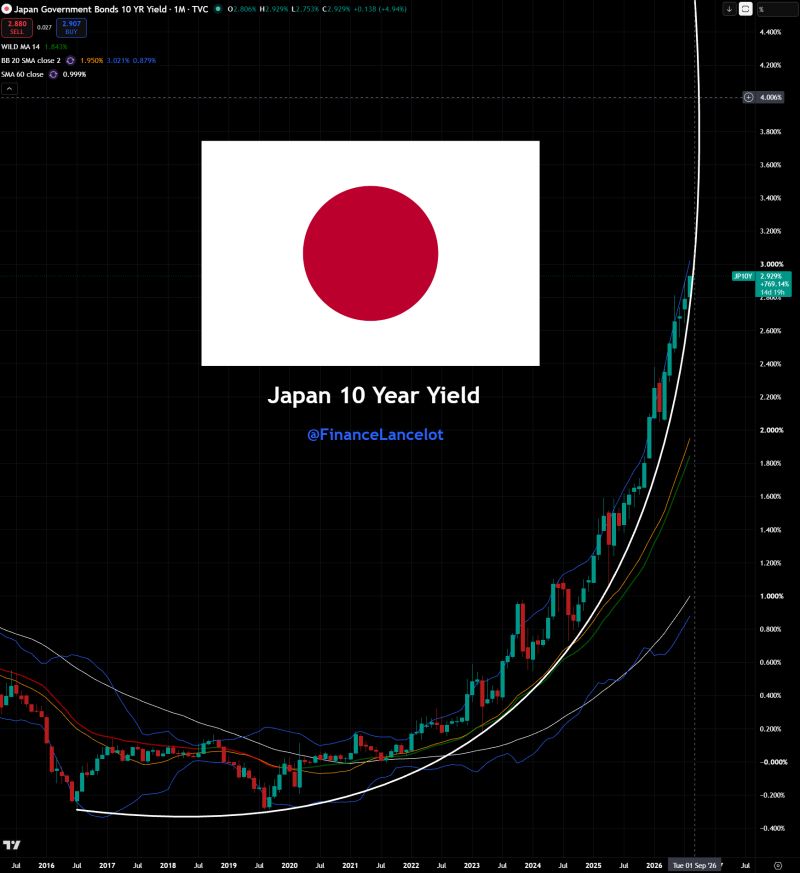
The 10-year JGB yield has hit 3% for the first time since 1996—doubling from roughly 1.5% in just 12 months. But the bigger story is who now sets the price. Foreign investors account for around 66% of monthly JGB trading volume, up from only 12% in 2009, as the Bank of Japan retreats from negative rates and massive bond purchases. Markets are responding: • A 92% probability of a BOJ rate hike by September • An October increase already more than fully priced in • Record debt-servicing costs of ¥36.6 trillion—around $230 billion—budgeted for the next fiscal year, up 17% For decades, the BOJ dominated Japan’s bond market. Now, market forces are taking control—and the cost of financing the world’s most indebted major economy is rising fast. Investors, not the BOJ, are increasingly setting the price of Japanese debt. Source: Global Markets Investor, Bloomberg
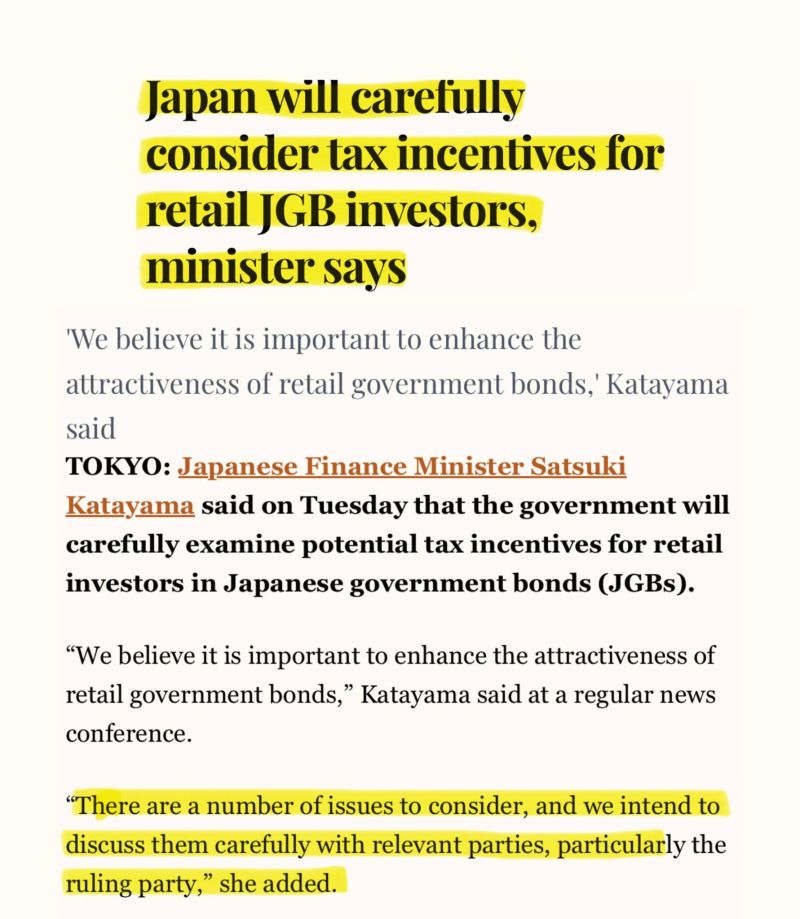
JAPAN IS TRYING TO FIND NEW BUYERS FOR ITS MASSIVE BOND MARKET.
For decades, the Bank of Japan was the buyer of last resort for Japanese government debt. But since 2024, the BOJ has been reducing its bond purchases — leaving a growing demand gap as yields rise. Now Tokyo wants households to help fill it. Japan’s Finance Ministry is reportedly considering adding government bonds to the New NISA tax-free investment program as part of its fiscal 2027 tax reforms. Some lawmakers are even pushing for inheritance-tax incentives. The challenge is huge: → BOJ owns roughly 50% of JGBs → Banks and institutions hold around 40% → Japanese households own just 2% Meanwhile, long-term Japanese yields are trading around levels not seen in decades. Japan spent years using its central bank to absorb government debt. Now it increasingly needs private investors to take over. The big question: Will Japanese households become the bond market’s new buyer of last resort? Source: Bull Theory
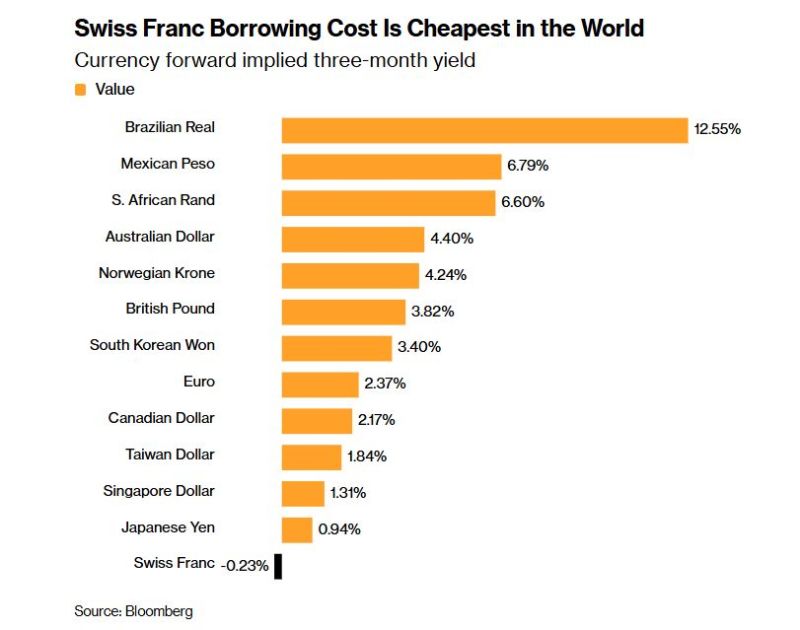
For decades, the Japanese yen has been the funding currency of choice for global carry trades.
But as volatility in Japan rises and the Bank of Japan gradually moves away from ultra-low interest rates, investors are increasingly looking for alternatives. One currency is emerging as a natural candidate: the Swiss franc. The logic is straightforward. Swiss interest rates remain close to zero, making the franc one of the cheapest major currencies in the world to borrow. At the same time, the Swiss National Bank remains attentive to excessive currency appreciation, reducing—at least in investors’ eyes—the risk of a sharp and uncontrolled strengthening of the franc. Positioning data suggests traders are taking notice. Hedge funds have pushed net short positions in the Swiss franc close to a two-month high, while speculative short positions in the yen have declined for a second consecutive week. The performance differential is already becoming visible. Over the past month, a carry trade funded in Swiss francs and invested in the Mexican peso would have generated a return of roughly 4%, compared with around 1.3% for the same trade funded in Japanese yen. The yen is unlikely to lose its status as the world’s dominant funding currency anytime soon. But the backdrop has changed. Expectations of higher Japanese interest rates, combined with the persistent risk of currency intervention, have made yen-funded carry trades less predictable. By contrast, Switzerland combines extremely low borrowing costs with relatively low interest-rate volatility. That is putting the franc firmly back on traders’ radar. There is, of course, a striking irony in all of this: one of the world’s ultimate safe-haven currencies is increasingly being borrowed to finance risk-taking elsewhere. The Swiss franc may still be a refuge when markets panic—but in calmer times, it is increasingly becoming the fuel behind the carry trade. Source: Bloomberg
Bloodbath in Asian Markets
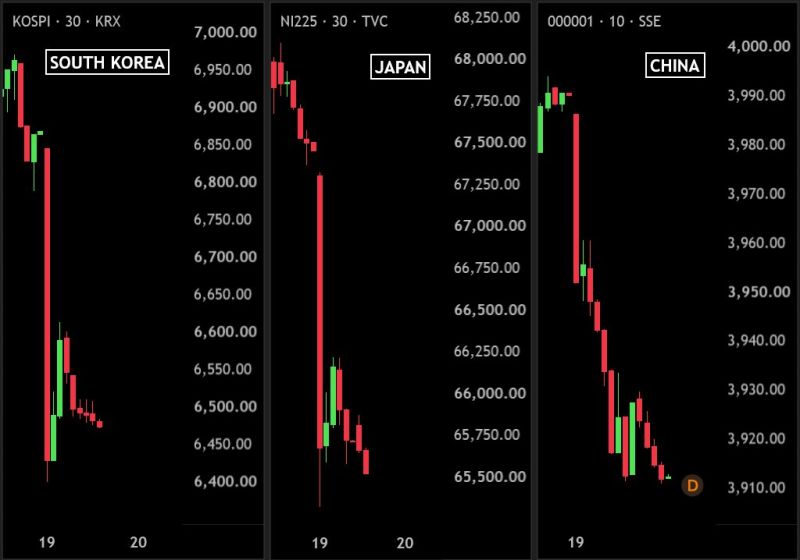
Over $650 BILLION has been wiped out from Asian stocks as semiconductor and tech stocks sell off across Asian markets. 🇰🇷 South Korea's KOSPI -5.5%, wiping out ₩279.7T ($186B). 🇯🇵 Japan's NIKKEI -3.1%, wiping out ¥36.7T ($232B). 🇨🇳 China's SSE -2%, wiping out ¥1.29T ($180B). 🇹🇼 Taiwan's stock market -1.5%, wiping out NT$1.80T ($55B). Source: Bull Theory
The 🇯🇵 Japanese 10 year yield just jumped to 2.93%.
Can the parabolic rise continue without hurting global bond markets and stocks? Source: Financelot
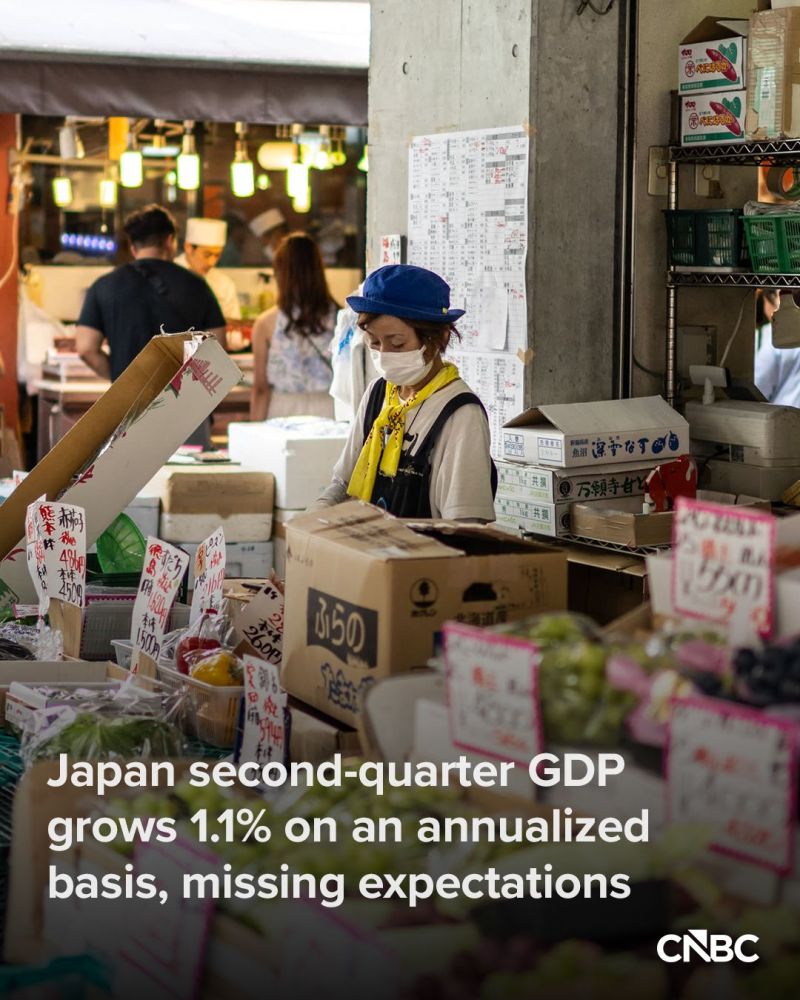
In case you missed it.. Japan’s economy expanded 1.1% in the second quarter on an annualized basis, missing expectations for 2% growth as softer domestic demand offset strong exports.
This is the first full quarter to include the impact of the Iran war, which has brought energy prices higher for business and households. Source: CNBC
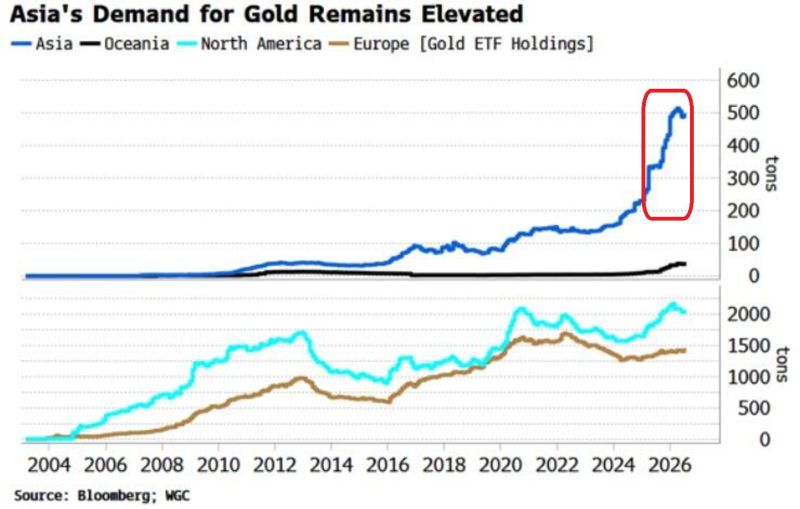
Gold demand in Asia remains exceptionally strong.
Asian gold ETF holdings have more than doubled over the past year, surpassing 500 tonnes for the first time this century, with China driving much of the surge. By contrast, gold ETF holdings in North America and Europe have remained broadly stable. And the macro backdrop supporting gold has barely changed: Government debt remains historically high Fiscal deficits remain elevated Non-bank credit continues to expand Leverage across the financial system remains substantial In other words, the structural case for gold remains firmly intact. What is changing is investor demand. Asian investors, particularly in China, are accumulating gold at an accelerating pace. And when structural macro support meets rising investment demand, the adjustment ultimately has to come through one place: The price of gold. Source: Bloomberg, Global Markets Investor
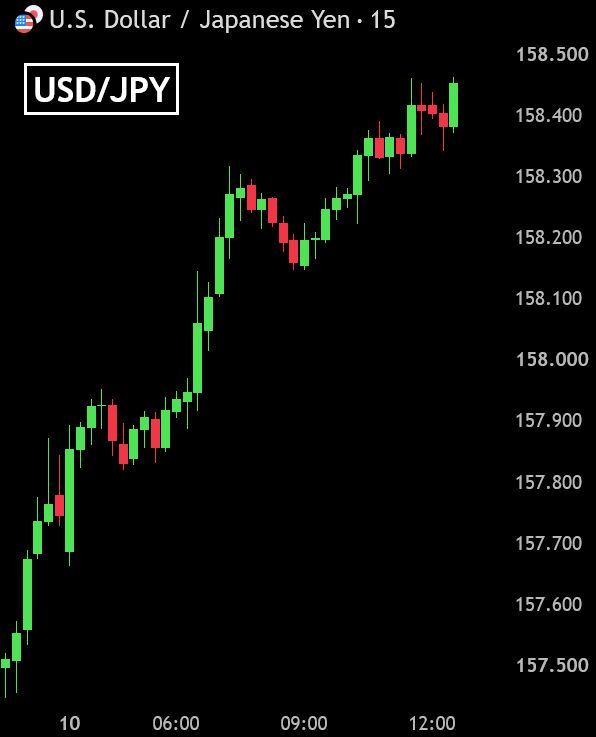
Japanese yen weakened past 158 per dollar.
Japan’s current account unexpectedly swung to a ¥923B deficit in June, its first since January 2025, versus expectations for a ¥1.512T surplus. Yen is currently the weakest G-10 currency in August as the effect of the joint US-Japan intervention fades. Bank of Japan also flagged rising inflation risks in its July summary of opinions, with one board member saying rate hikes could come faster. Source: Bull Theory