
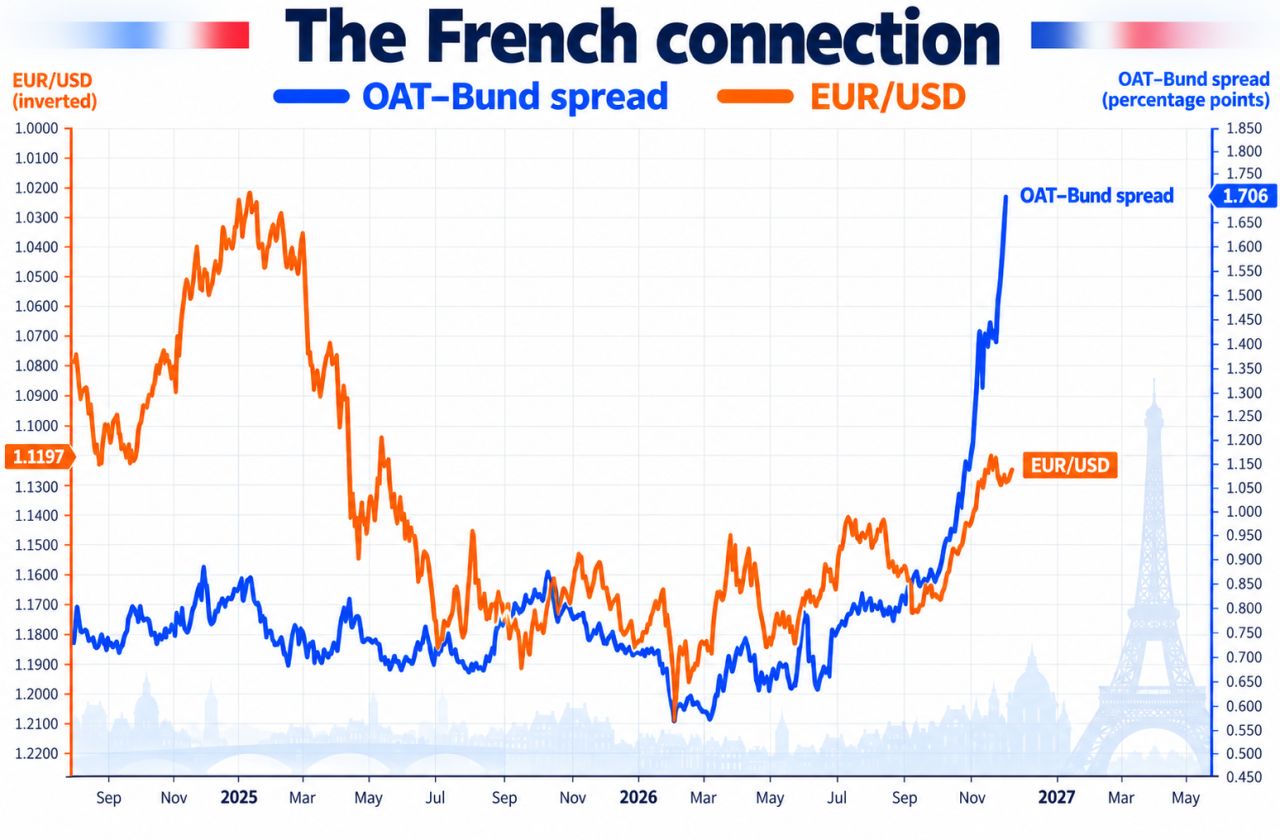
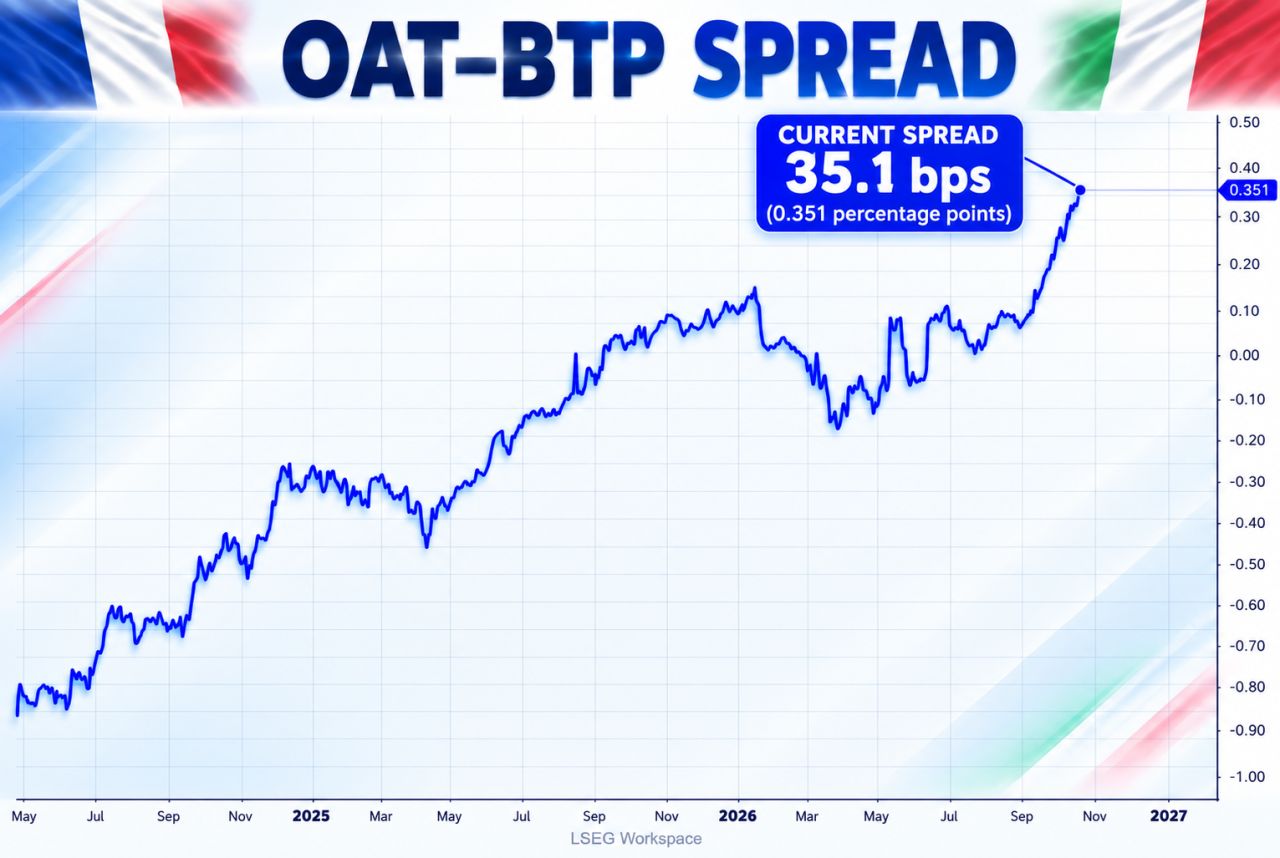
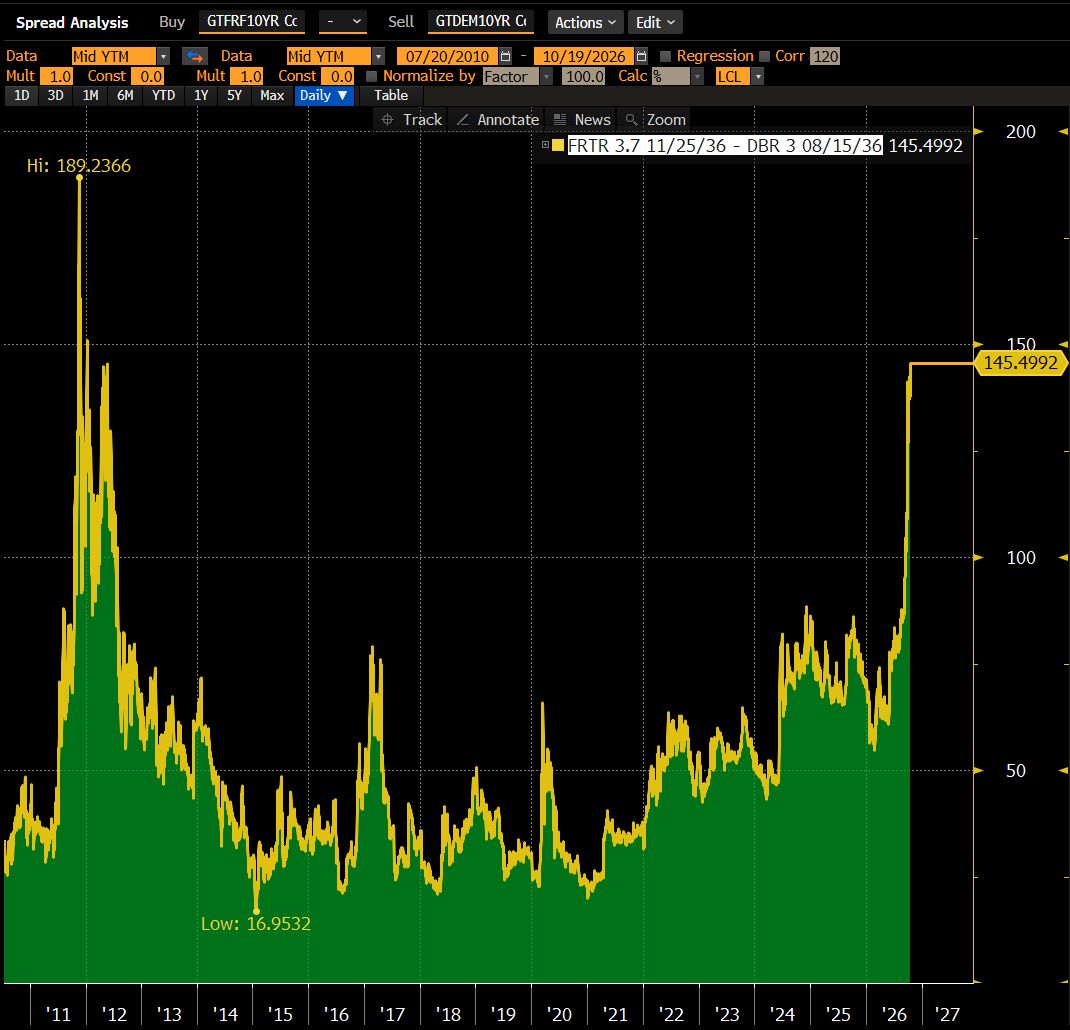
The OAT-BTP spread continues to blow out as France increasingly trades like the European periphery.
Meanwhile, European banks (SX7E) remain under heavy selling pressure. Source. TME
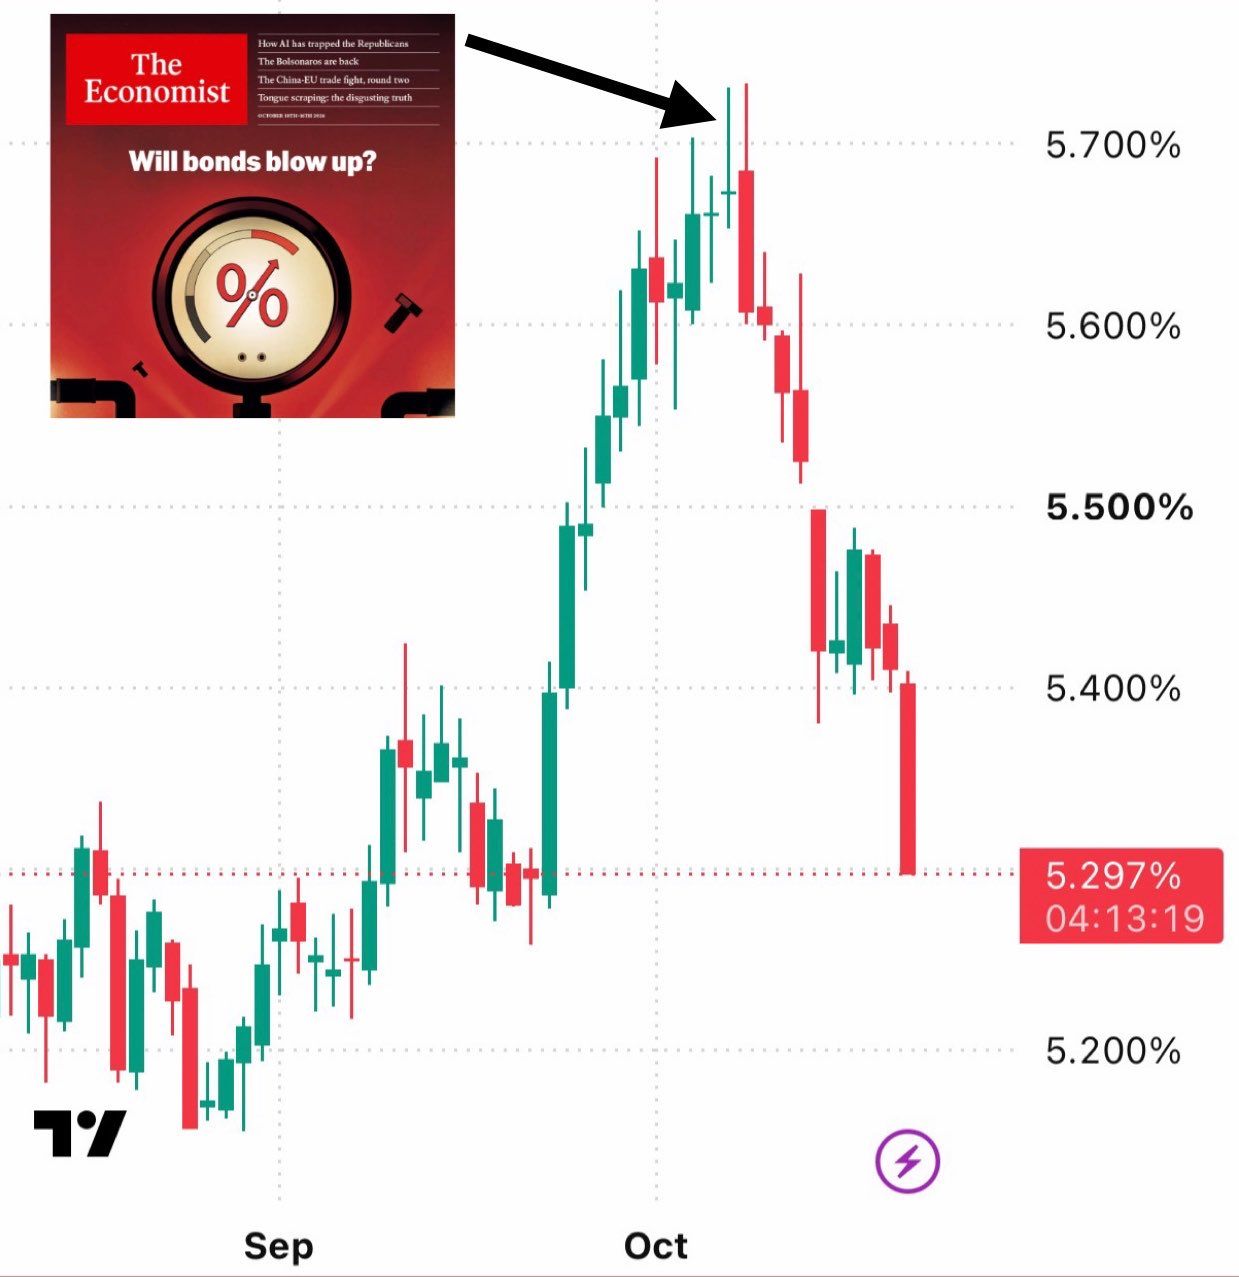
The Economist cover remains undefeated.
Source: Geiger Capital
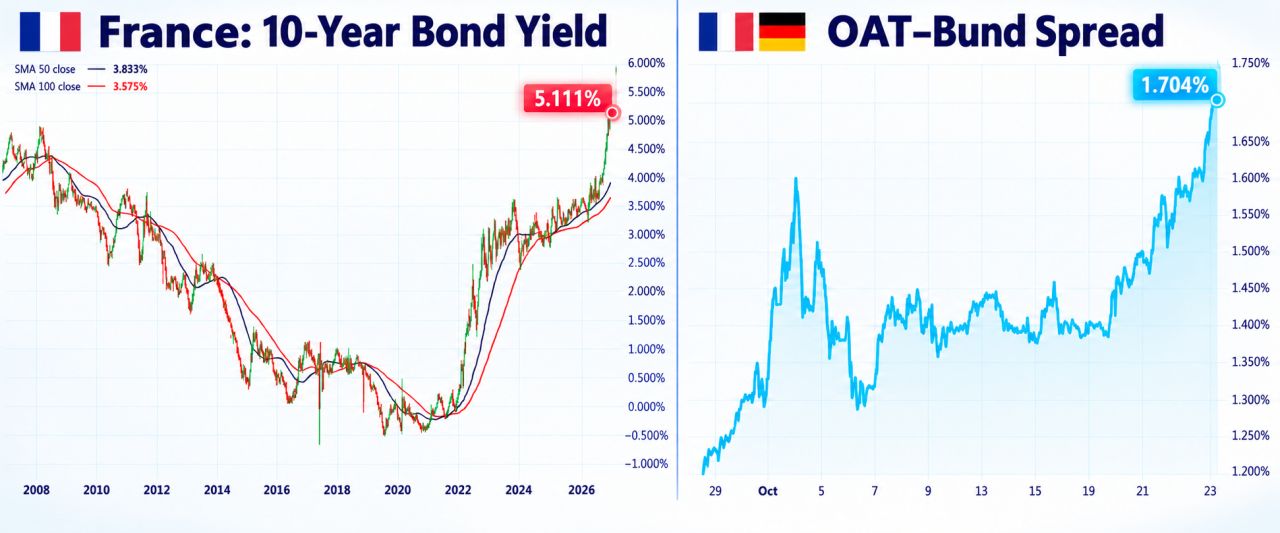
The situation continues to tighten for France on the markets...
🔹10-year yield = 5.11% 🔹OAT-Bund spread > 170 bps Source: Alexandre Baradez
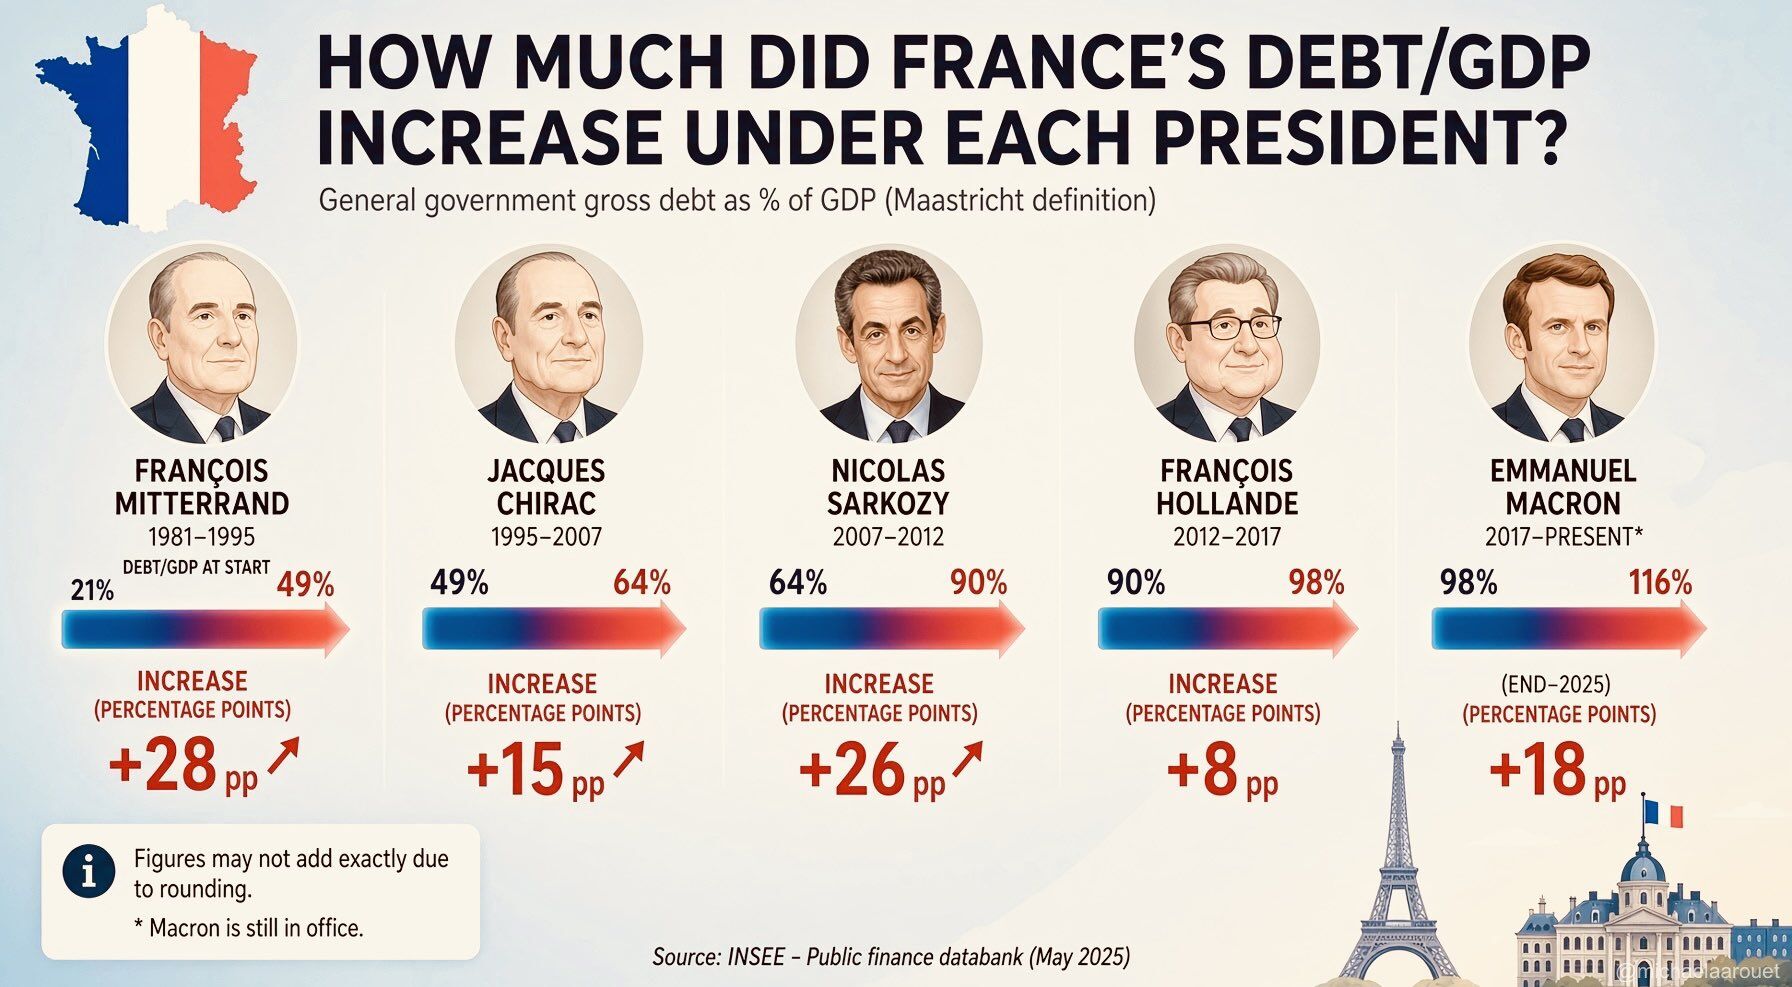
France’s debt problem has no single political owner
Decades of fiscal slippage have pushed debt towards 120% of GDP. Now the arithmetic is tightening: Higher yields → higher interest costs → wider deficits → more debt. Modest growth makes that cycle harder to break. Reforms face fierce resistance. Political instability makes lasting consolidation harder. France’s economic model faces a tougher test as borrowing costs rise and debt accumulates. The question reaches beyond Paris: Can France stabilise its finances before market pressure turns a national fiscal problem into a eurozone crisis?
France’s long-term borrowing costs have hit 5%
This benchmark was last reached in 2002. Investors grow increasingly concerned about the stability of the country’s politics and the state of its public finances. Meanwhile, Deutsche CEO Sewing sounds the alarm on #France: Its fiscal & political instability is a “wake up call” for Europe. The bond mkt is flashing red: France’s 10y spread over Germany has surged to 156bps, highest since 2011. Not a debt crisis yet, Sewing says. Source. HolgerZ, FT
The European sovereign problem is increasingly becoming a France problem
The OAT-BTP spread continues marching higher, highlighting just how dramatically the market is redrawing Europe's traditional core/periphery divide. Source: TME
France's 10-year bond yields are surging to new post-2012 highs relative to German 10-year yields.
Source: Bloomberg, Lisa Abramowicz @lisaabramowicz1 on X
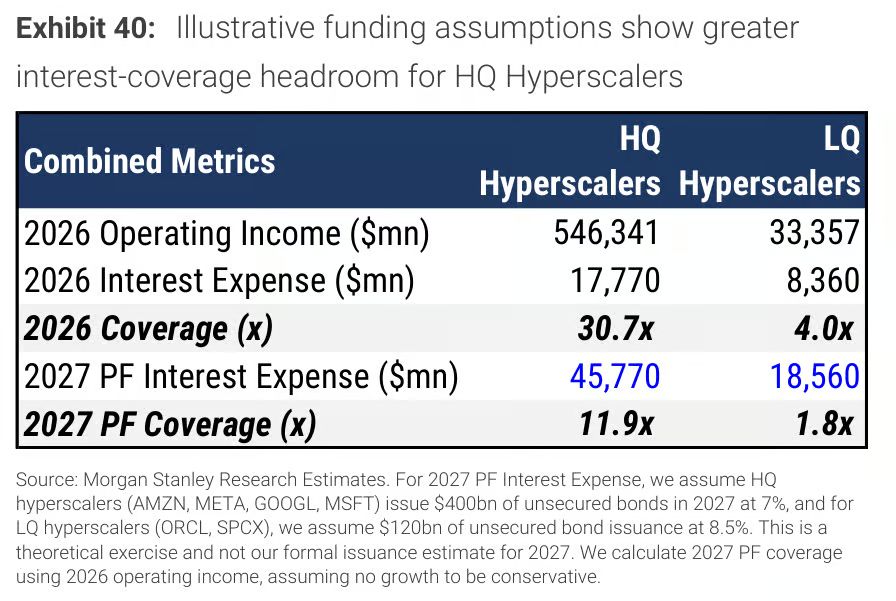
According to MS, AA-rated hyperscalers are "mostly price insensitive to higher interest rates," since they start from interest coverage above 30x.
The problem is everyone else. In an illustrative exercise, MS has the high-quality hyperscalers issuing $400 billion at 7% next year, which takes coverage from 30.7x to a still-comfortable 11.9x. But give Oracle and SpaceX $120 billion at 8.5%, and their combined coverage collapses from 4.0x to just 1.8x. Source: zerohedge