
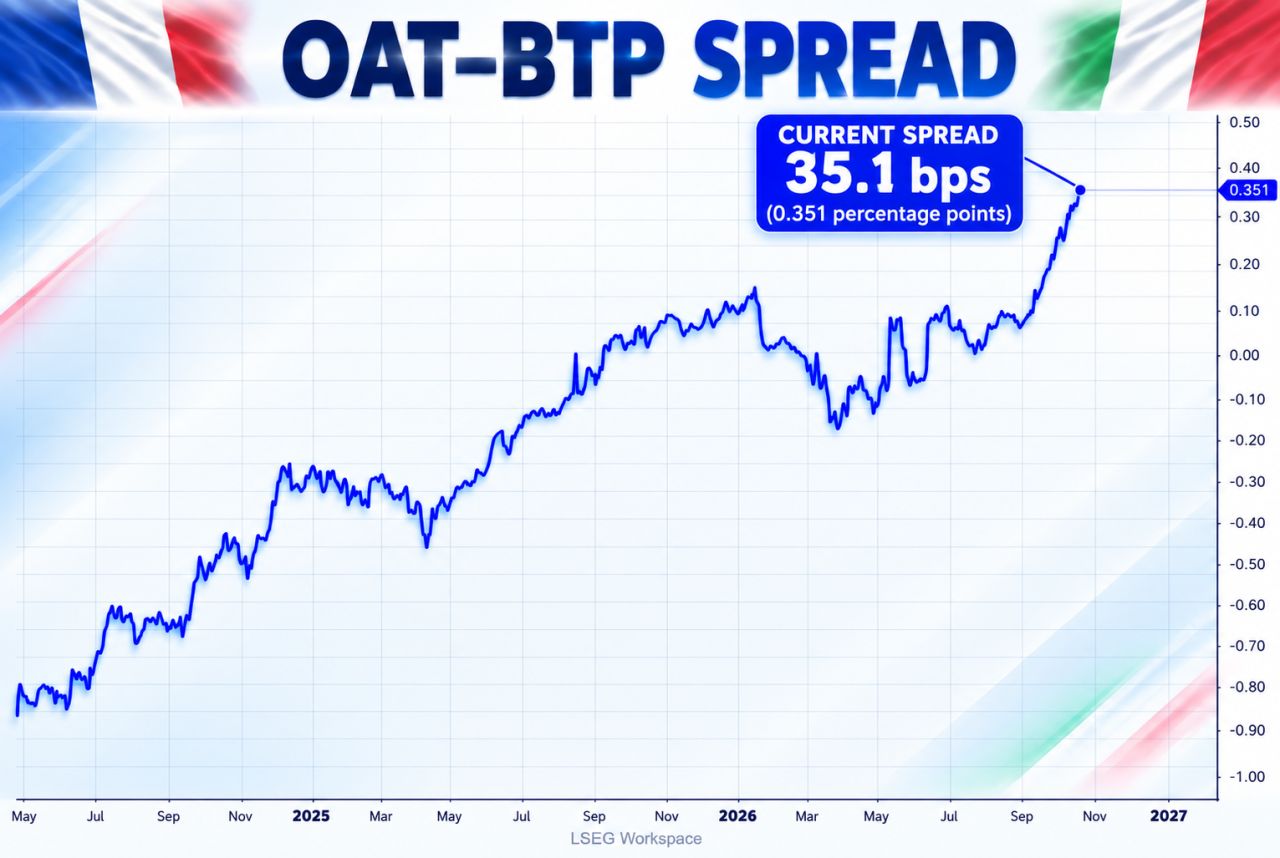
The European sovereign problem is increasingly becoming a France problem
Disclaimer
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Related Articles
Meanwhile, today's Eurostat report shows eurozone industrial production contracted another 1.1% yoy. Europe’s energy shock is becoming an industrial competitiveness crisis. European diesel prices are approaching $200 per barrel, while eurozone industrial production has contracted by another 1.1% year on year. Germany’s industrial output is already almost 10% below its 2021 level. Another energy shock is hitting an industrial base with limited room to absorb it. The transmission mechanism is clear: → Higher transportation costs. → Higher production costs. → Renewed inflationary pressure. But pricing power has limits. When businesses can no longer pass higher costs on to customers, margins compress. Production is reduced. Investment is postponed. More factories become economically unviable. This is the risk of another stagflationary shock: weaker activity alongside higher prices. For the ECB, the dilemma is increasingly difficult. Raising rates could contain inflation, but would also weaken demand, increase sovereign financing pressures and accelerate industrial decline. Europe faces a growing risk that a temporary energy shock leaves permanent damage to its industrial capacity. Source: Lukas Ekwueme @ekwufinance Bloomberg
Source: Bloomberg, Lisa Abramowicz @lisaabramowicz1 on X
The problem is everyone else. In an illustrative exercise, MS has the high-quality hyperscalers issuing $400 billion at 7% next year, which takes coverage from 30.7x to a still-comfortable 11.9x. But give Oracle and SpaceX $120 billion at 8.5%, and their combined coverage collapses from 4.0x to just 1.8x. Source: zerohedge