
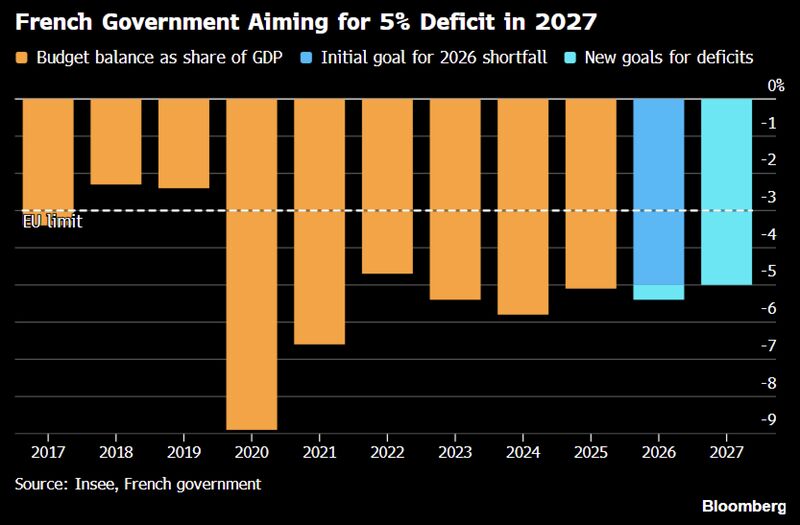
In case you missed it... France vows to cut its deficit to 5% of GDP in 2027 after missing the 2026 target.
Disclaimer
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Related Articles
The Bank of Japan reaffirmed that it will continue raising interest rates as growth and inflation evolve. Yet the yen weakened immediately after the announcement. The market’s verdict was clear: 25 basis points is not enough. Even with the policy rate now at 1.25%, the interest-rate differential remains wide—and so does the incentive to borrow in yen and invest in higher-yielding currencies. If Japan wants to support the yen without hiking more aggressively, it may have to return to FX intervention: selling dollar assets and using its reserves to buy yen. But intervention only buys time. It does not solve the underlying rate gap. The longer the BOJ waits to close that gap, the more aggressive future rate hikes may ultimately need to be. Key details: 1. BOJ voted 7-2 in favour of raising interest rates to 1.25%. 2. BOJ warns underlying inflation could rise above its 2% target. 3. Inflation pressure is spreading from producer prices into consumer prices. 4. Inflation expectations continue to rise. 5. Wage increases are increasingly being passed into selling prices. 6. Weak yen, higher oil prices and strong AI-related demand are adding inflation pressure. 7. Japan’s economy is still recovering moderately, supported by employment, income growth and AI-related demand. 8. CPI is expected to accelerate clearly above 2% from the second half of FY2026. 9. BOJ still says financial conditions remain accommodative despite the hike. 10. Future hikes will depend on economic activity, prices and financial conditions. Governor Ueda’s remarks will be closely watched for clues on the timing and pace of further hikes. Source: Bull Theory
As expected, the Fed raised rates by 25 basis points in a unanimous decision The dot plot showed that 16 of 18 participants expect at least one additional hike this year. However, this does NOT appear to be the start of an aggressive tightening cycle. Policymakers do not project further increases in the federal funds rate over the following years. A unanimous rate-hike decision, and large majority also signaling at least one more hike in 2026 hides the reality that 2027 outlooks are massively divided with four members signaling a 'policy error' implicitly with 3 seeing 2 cuts and 1 seeing 4 cuts... The statement and dots were more hawkish than expected overall as The Fed took away the projected median cut next year. October odds initially declined but then jumped (right before Midterms?) to 57% while December odds of a hike jumped to 75%... While noisy, 2027 rate-hike expectations rose to around 40bps (2026 expectations are now for another 30bps)... 👉 Warsh explained that a resilient labour market, persistent inflation concerns and geopolitical tensions had shifted the committee in favour of a hike. 👉He described the hike as removing a degree of accommodation. In practice, the Fed may be reversing the three rate cuts delivered in 2025—leaving room for UP TO TWO additional hikes. Warsh also suggested that intense competition for capital, particularly from technology hyperscalers, may be contributing to higher US bond yields. 🔴 Conclusion: Yesterday’s hike, and potentially another 25-basis-point increase this year, gives the Fed time to see whether oil prices retreat. A third hike could follow in early 2027 if necessary, fully reversing last year’s easing cycle. Source image: zerohedge