
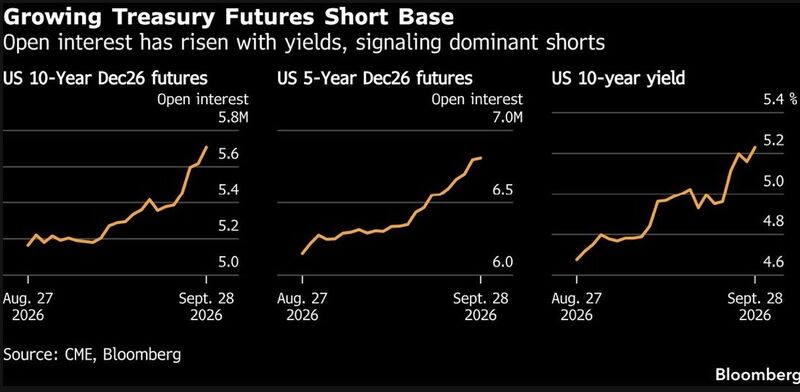
Short positions are surging in Treasuries.
Disclaimer
This marketing document has been issued by Bank Syz Ltd. It is not intended for distribution to, publication, provision or use by individuals or legal entities that are citizens of or reside in a state, country or jurisdiction in which applicable laws and regulations prohibit its distribution, publication, provision or use. It is not directed to any person or entity to whom it would be illegal to send such marketing material. This document is intended for informational purposes only and should not be construed as an offer, solicitation or recommendation for the subscription, purchase, sale or safekeeping of any security or financial instrument or for the engagement in any other transaction, as the provision of any investment advice or service, or as a contractual document. Nothing in this document constitutes an investment, legal, tax or accounting advice or a representation that any investment or strategy is suitable or appropriate for an investor's particular and individual circumstances, nor does it constitute a personalized investment advice for any investor. This document reflects the information, opinions and comments of Bank Syz Ltd. as of the date of its publication, which are subject to change without notice. The opinions and comments of the authors in this document reflect their current views and may not coincide with those of other Syz Group entities or third parties, which may have reached different conclusions. The market valuations, terms and calculations contained herein are estimates only. The information provided comes from sources deemed reliable, but Bank Syz Ltd. does not guarantee its completeness, accuracy, reliability and actuality. Past performance gives no indication of nor guarantees current or future results. Bank Syz Ltd. accepts no liability for any loss arising from the use of this document.
Related Articles
France now pays more to borrow than Italy. And Vanguard is warning the pressure could intensify. The $12 trillion asset manager sees deteriorating creditworthiness, political paralysis and an election that could bring further fiscal loosening. The bond market is already sending a message: 📈 French 10-year yields topped 4.8%, their highest since 2008. 📈 The spread over Germany briefly exceeded 120 basis points. 📈 France’s borrowing premium over Italy reached a record. Meanwhile, the deficit is expected to reach 5.5% of GDP this year. Next year’s planned debt issuance: a record €340 billion. Vanguard sees a German spread above 150 basis points as a strong possibility if public finances worsen. Some investors see a buying opportunity, arguing the risks are already priced in. But the central question remains: Can France restore fiscal credibility before markets demand an even higher price? Source: FT
Core PCE YoY: 3.0% (Est. 3.3%, Prior 3.3%) Core PCE MoM: 0.2% (Est. 0.3%, Prior 0.2%) PCE YoY: 3.4% (Est. 3.7%, Prior 3.7%) PCE MoM: 0.3% (Est. 0.3%, Prior 0.2%) Historical YoY figures were revised downward in the 2026 National Economic Accounts annual update, driven by BEA methodology changes to price-versus-quantity splits in portfolio management, legal services, and computer software. The softer inflation picture is easing pressure on the Fed to stay tighter for longer, with October rate hike odds falling again. That is generally SUPPORTIVE for stocks, precious metals and crypto, as lower rate expectations can boost liquidity and risk appetite. Source: Coinbureau, Wall St Engine. Macro