
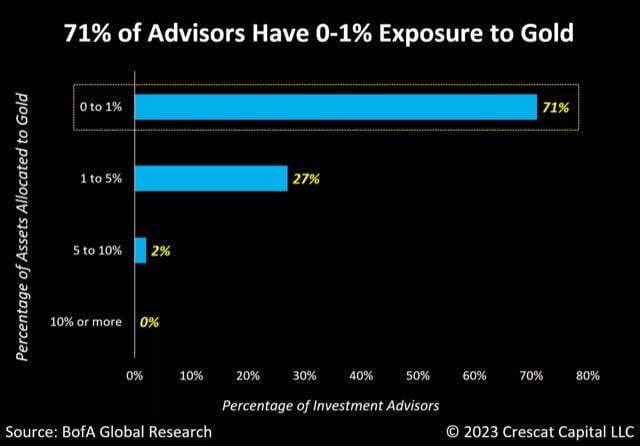
As highlighted by Tavi Costa, one of the positives for gold today is the consistent neglect of the metal as a defensive alternative over the past few decades
This is evident in the significant underrepresentation of precious metals among traditional investment strategists. Source: Crescat Capital
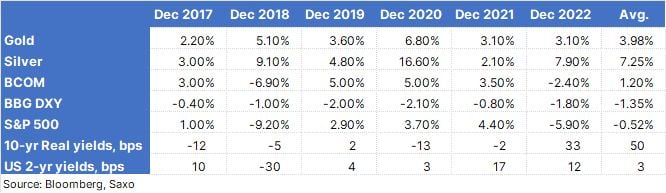
Gold has seen a "Santa" rally every December since 2017 with the average monthly gain near 4%. (silver 7.25%).
Source: Ole S Hansen, Saxo
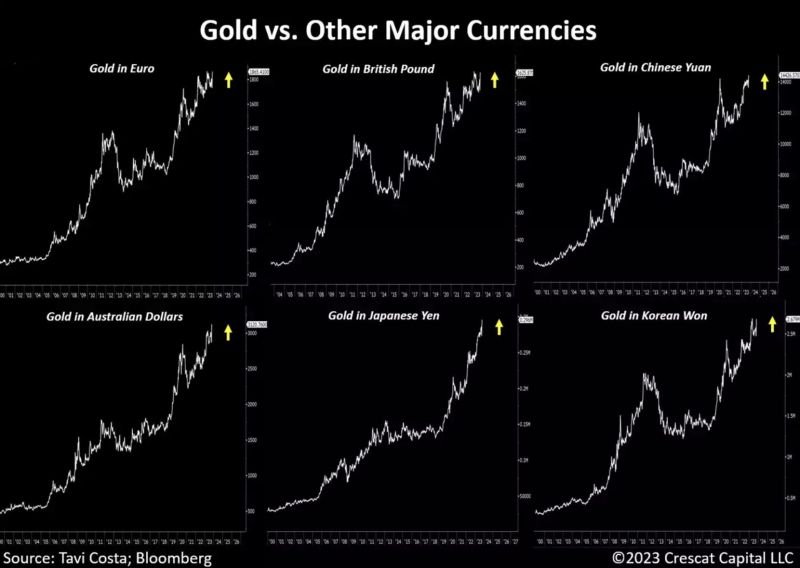
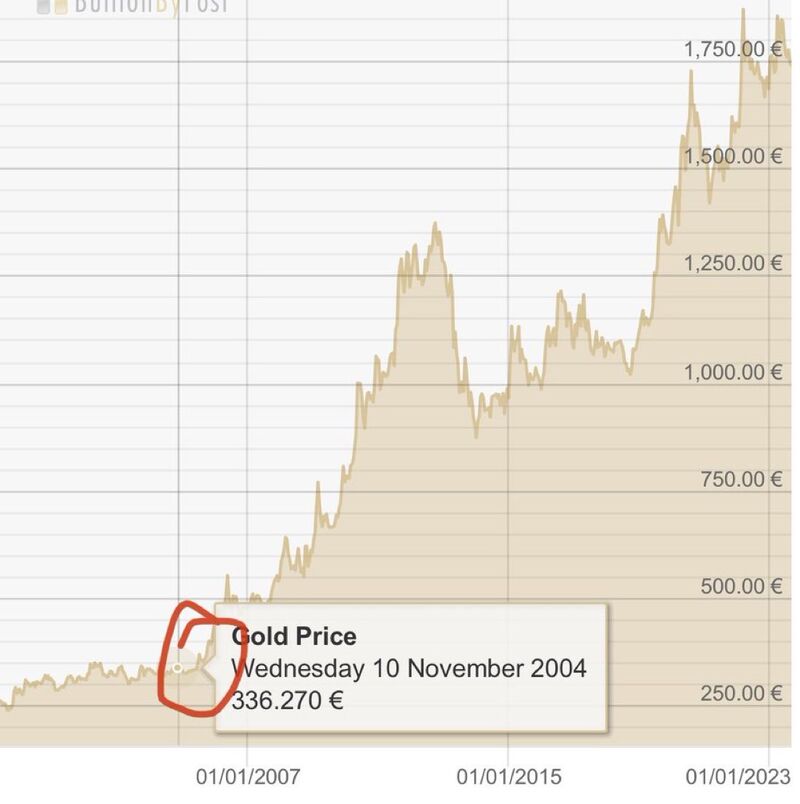
Be careful not to look at gold only against the dollar. Gold is at its highest against many FIAT currencies
But even the $2,000 an ounce level is intriguing: despite clearly positive real rates and the appreciation of the greenback, gold is close to all-time highs. Looking forward, two scenarios are possible: o 1) Gold is overvalued and should soon depreciate o 2) Gold is seen as a safe haven against geopolitical uncertainty, but also against the political disorder in Washington and the declining confidence in the Fed. If this is the case, a possible depreciation of the dollar and a fall in the real interest rate could benefit the yellow metal. Bottom-line: Gold remains an attractive portfolio diversifier Source chart: Tavi Costa, Bloomberg
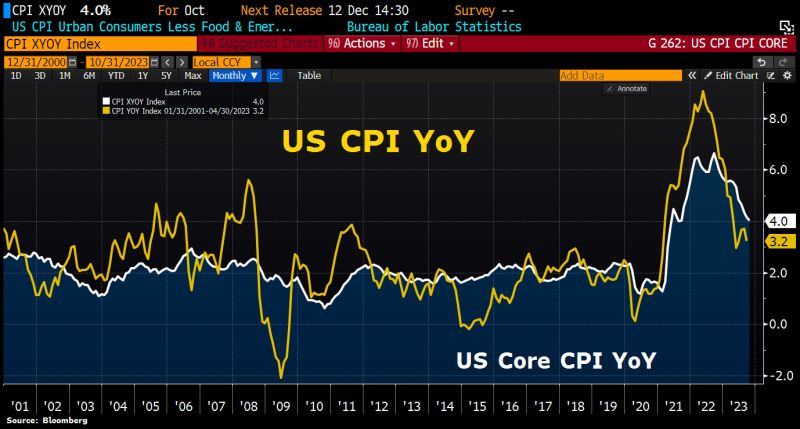
US inflation data for Oct undershoot consensus
Headline dropped to +3.2% from 3.7% in Sep vs 3.3% expected, Core CPI dropped to 4.0% from 4.1% vs 4.1% expected. Dollar and Yields plunge. - Following two months of higher than expected US CPI numbers (mainly driven by higher energy prices and healthcare costs), the October CPI print was expected slow materially (from 3.7% to 3.3% yoy on headline CPI) while the core was expected to remain unchanged at 4.1%. But today’s CPI print is a miss across the board with both headline and core numbers coming in below expectations on both a sequential and annual basis. - Headline CPI came in at 3.2%, below the 3.3% expected, while MoM CPI also missed expectations, being vs. consensus at +0.1% and sharply below last month's 0.4%. Source: Bloomberg, HolgeZ, www.zerohedge.com
Reminder that this happened when the Gold Spot ETF was approved
Source: Bitcoin for Freedom
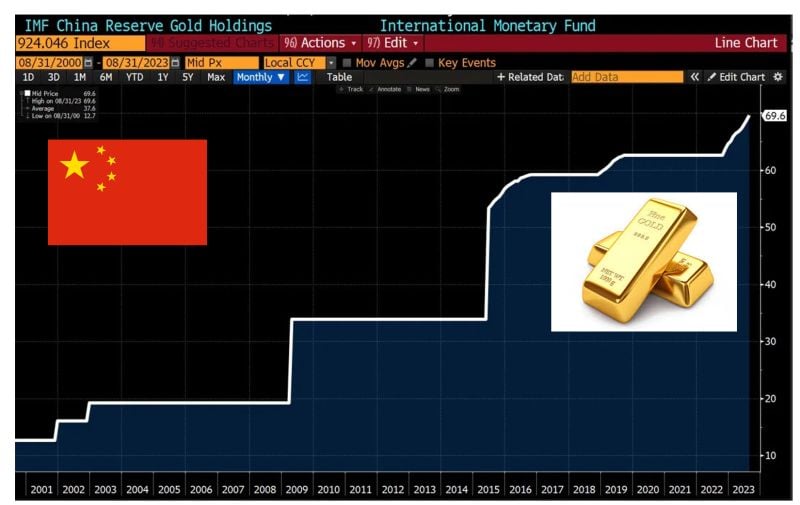
China reserve gold holdings as per IMF
Source: Bloomberg
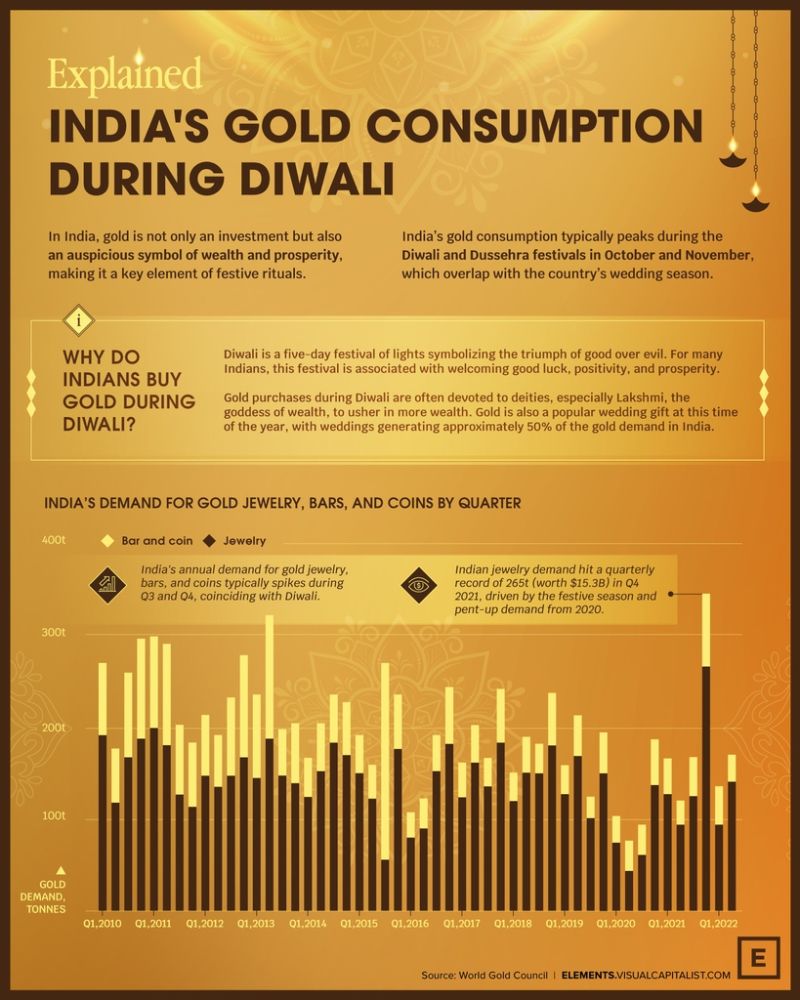
Explained: India’s Gold Demand During Diwali - by Elements, Visual Capitalist
In India, gold’s significance goes far beyond investment and jewelry. The yellow metal is woven into India’s cultural history and is revered by a population of over 1.3 billion.
Even with gold near ATHs, central banks are still buying record tonnage of yellow metal...
Source: FT
